Umang Sisodia • • 4 min read • 1 view

PPF, Sukanya Samriddhi & SCSS Interest Rates Unveiled: What Investors Need to Know
PPF, Sukanya Samriddhi & SCSS Interest Rates Unveiled: What Investors Need to Know

Government’s New Interest Rate Announcement

India’s Ministry of Finance has just declared the latest interest rates for three cornerstone small‑saving schemes – Public Provident Fund (PPF), Sukanya Samriddhi Yojana (SSY) and the Senior Citizens Savings Scheme (SCSS). The decision, announced in a televised press conference on 30 September 2026, locks PPF at 7.1 %, SSY at 8.2 %, while SCSS will continue to yield 7.9 % for the next fiscal year.

PPF – 7.1 % for the Next Five Years

The PPF, a 15‑year tax‑saving instrument, has seen its rate rise from 6.8 % last year. The new 7.1 % rate is expected to attract both salaried and self‑employed investors seeking a safe, long‑term avenue for wealth creation.

Sukanya Samriddhi Yojana – 8.2 % for Girl‑Child Savings

SSY, introduced in 2015, offers the highest return among small‑saving schemes. With an 8.2 % rate, the government signals a continued focus on female empowerment and financial inclusion.

SCSS – 7.9 % for Senior Citizens

SCSS, a five‑year scheme for individuals aged 60 + , retains its 7.9 % rate, reinforcing the safety net for retirees.
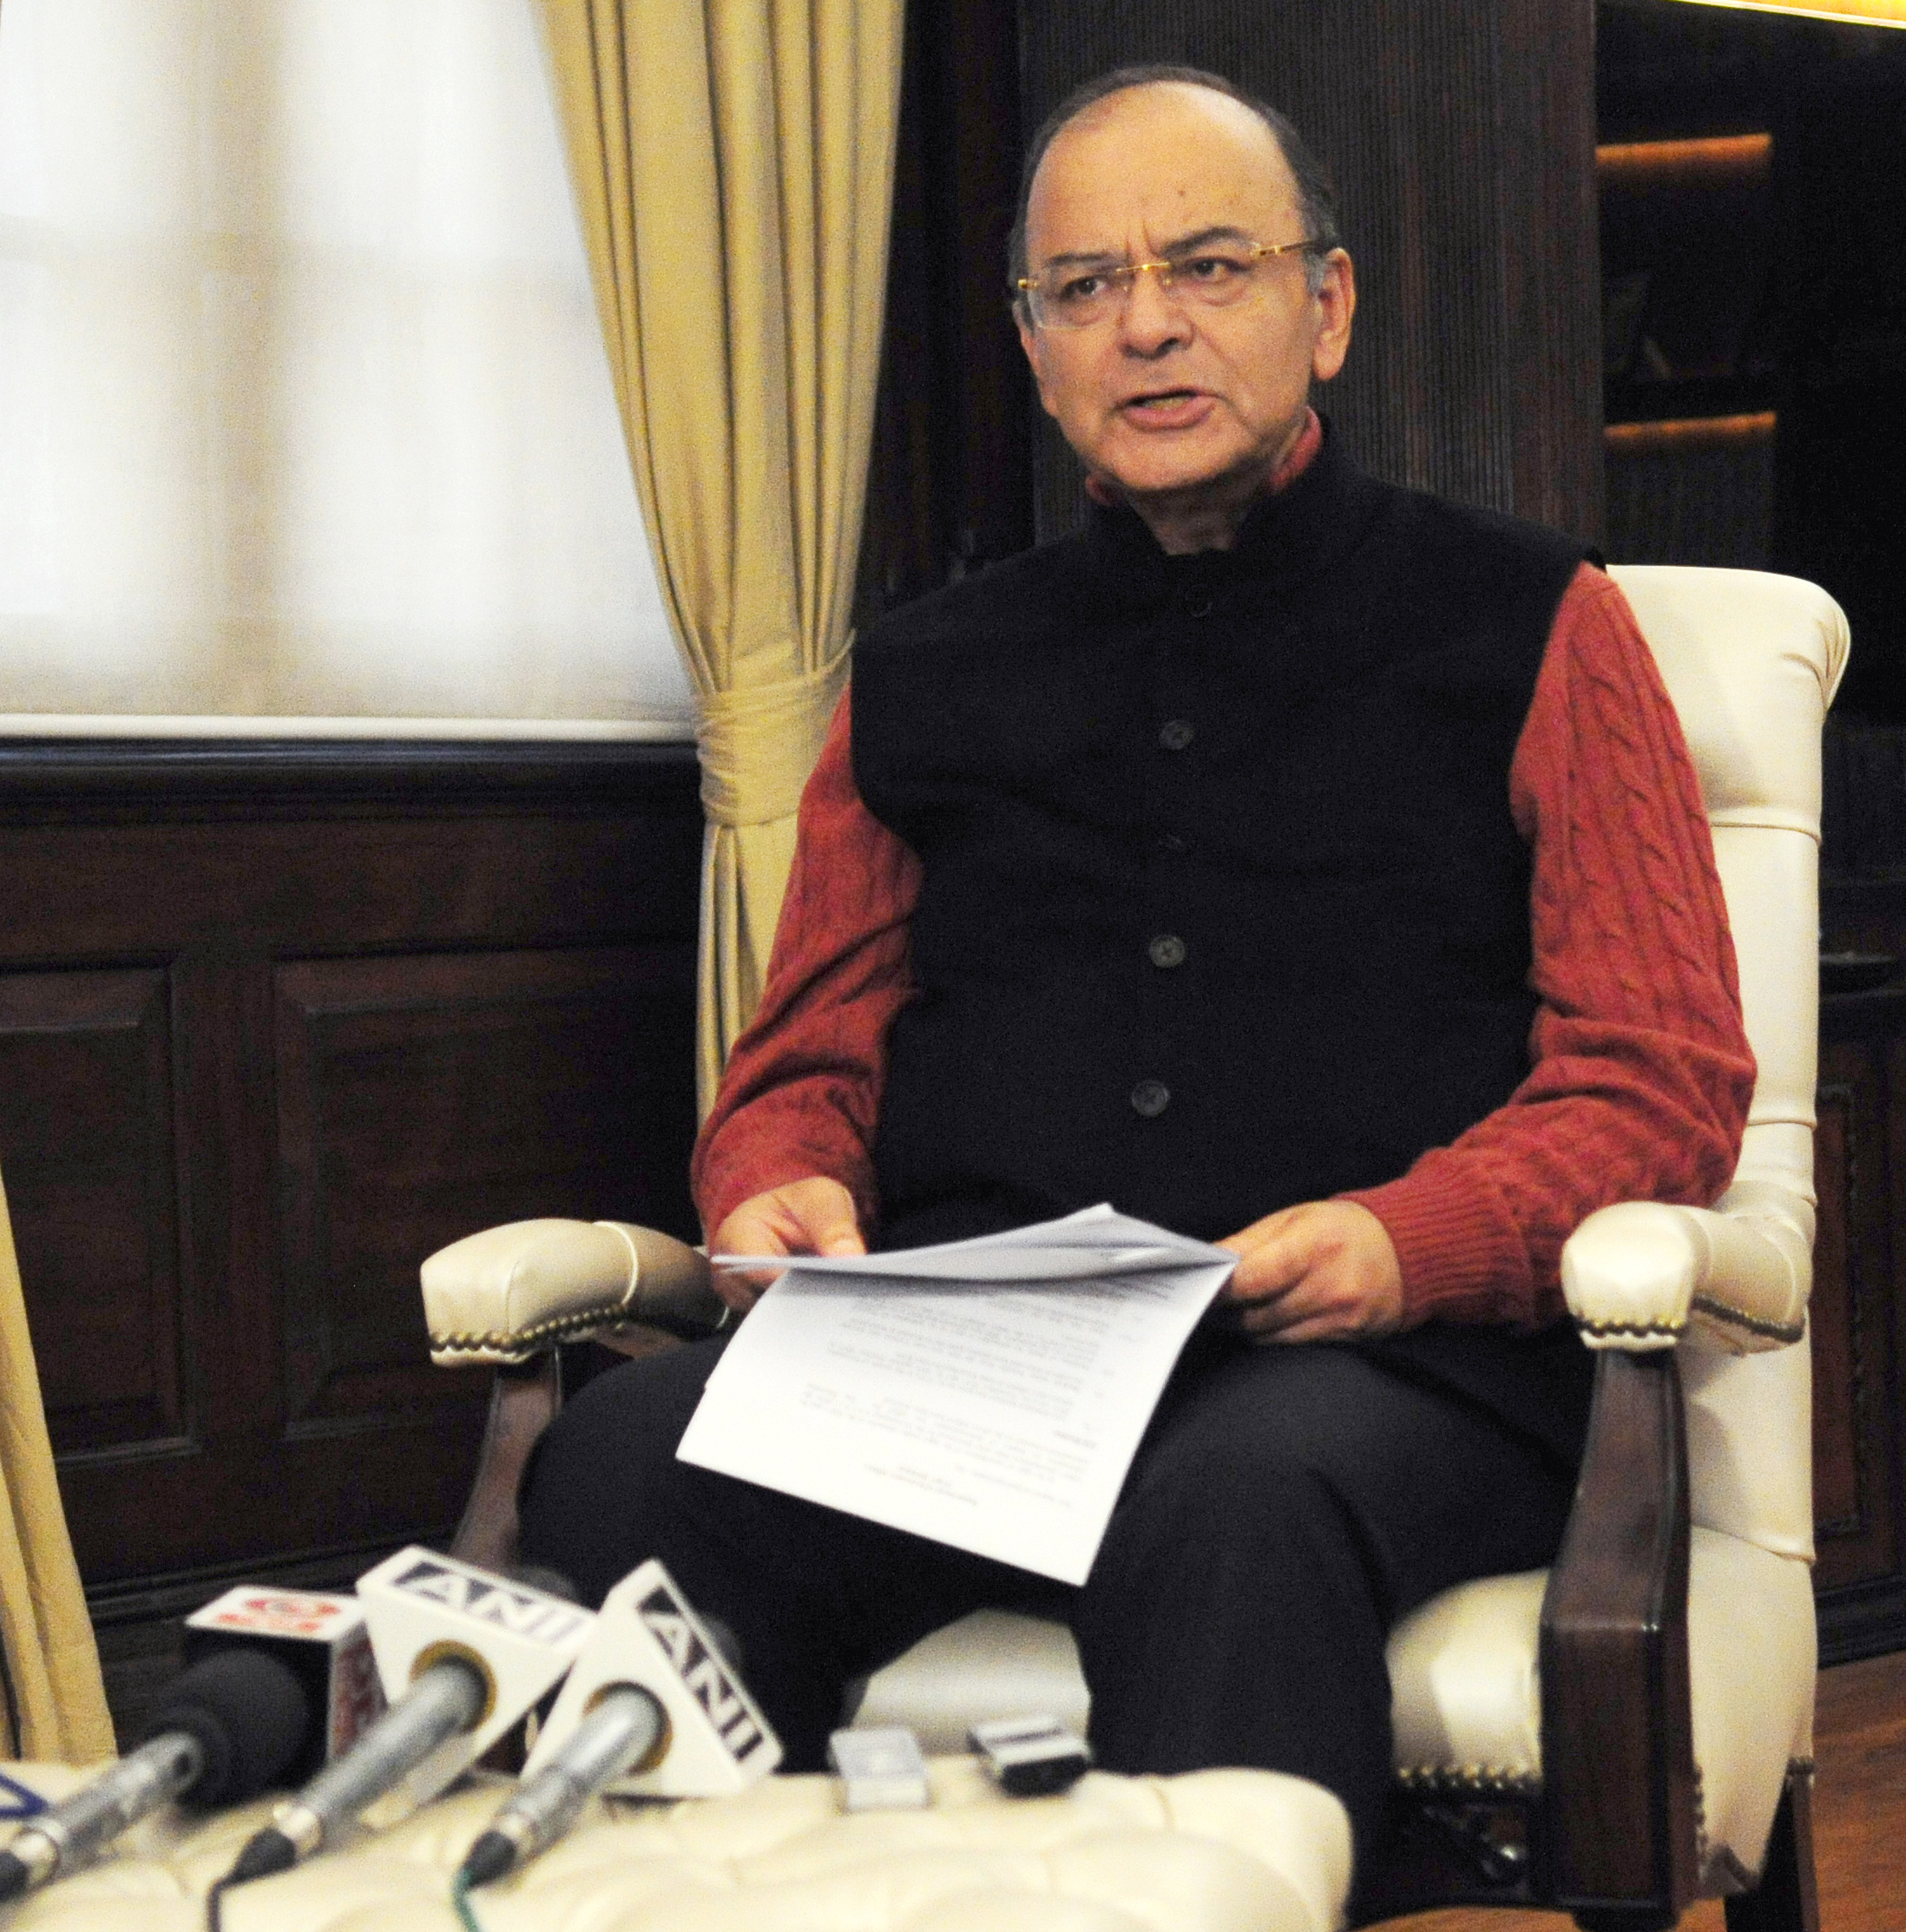
Indian Ministry of Finance press briefing Delhi Indian Ministry of Finance press briefing Delhi

The announcement has sparked a surge in searches for “ब्याज” (interest) on Google Trends India, crossing the 2,000‑search threshold within hours. Several factors fuel this spike:

  • High‑stakes decision: Small‑saving rates directly affect millions of depositors.
  • Market timing: Investors are recalibrating portfolios ahead of the upcoming budget.
  • Media amplification: Leading outlets like Aaj Tak, IndiaTimes and Dainik Bhaskar ran front‑page stories, amplifying public curiosity.

“The revised rates are designed to keep small savers incentivised while maintaining fiscal prudence,” – Finance Minister Jitendra Singh (press conference, 30 Sept 2026).

Historical Context of Small‑Saving Schemes

Since the 1950s, the Indian government has used small‑saving schemes to channel household savings into public debt, stabilising the fiscal balance. Over the past decade, rates have trended downwards, mirroring global low‑interest environments. The recent upward tick reflects:

  • Improved fiscal space after a surplus in the 2025‑26 financial year.
  • Rising inflation expectations, prompting the RBI to tighten monetary policy, which in turn nudges government rates upward.
  • Policy intent to boost female‑focused savings, evident in the premium SSY rate.

Impact on Investors and the Economy

For Retail Depositors

  • Higher returns: The uplift translates to an extra ₹1,200 per ₹100,000 invested annually in PPF.
  • Liquidity considerations: While PPF remains locked for 15 years, SCSS offers quarterly interest payouts, appealing to retirees.

For the Government

  • Cost of borrowing: The marginal rise increases the interest burden on the sovereign debt portfolio, but the impact is modest given the limited size of these schemes relative to total debt.
  • Fiscal signaling: A stable or rising rate signals confidence in macroeconomic stability, potentially attracting foreign portfolio inflows.

For the Broader Economy

  • Consumption boost: Higher interest income can spur household spending, especially among retirees.
  • Savings‑investment channel: By keeping small‑savers within the formal financial system, the government ensures a steady flow of low‑cost funds for infrastructure projects.

Key Takeaways

  • PPF at 7.1 %, SSY at 8.2 %, SCSS at 7.9 % – rates are locked for the next fiscal year.
  • The announcement triggered a Google Trends surge due to its direct impact on millions of Indians.
  • Historical context shows a strategic shift toward higher rates after a period of low‑interest policies.
  • Investors should reassess allocation to small‑saving schemes, especially if seeking tax‑benefits and stable returns.
  • The move may bolster consumer confidence and modestly increase the government’s borrowing cost, but overall fiscal health remains strong.

Stay tuned for our next deep‑dive on how these rates compare with bank fixed deposits and the emerging trend of digital‑only savings platforms.


Original Reporting & Source: Google Trends (India)
Discussion (0)

Sign in to join the discussion.

No comments yet. Be the first to start the conversation!

| |

PPF, Sukanya Samriddhi & SCSS Interest Rates Unveiled: What Investors Need to Know

By Umang Sisodia • 4 min read • 1 view

Government’s New Interest Rate Announcement

India’s Ministry of Finance has just declared the latest interest rates for three cornerstone small‑saving schemes – Public Provident Fund (PPF), Sukanya Samriddhi Yojana (SSY) and the Senior Citizens Savings Scheme (SCSS). The decision, announced in a televised press conference on 30 September 2026, locks PPF at 7.1 %, SSY at 8.2 %, while SCSS will continue to yield 7.9 % for the next fiscal year.

PPF – 7.1 % for the Next Five Years

The PPF, a 15‑year tax‑saving instrument, has seen its rate rise from 6.8 % last year. The new 7.1 % rate is expected to attract both salaried and self‑employed investors seeking a safe, long‑term avenue for wealth creation.

Sukanya Samriddhi Yojana – 8.2 % for Girl‑Child Savings

SSY, introduced in 2015, offers the highest return among small‑saving schemes. With an 8.2 % rate, the government signals a continued focus on female empowerment and financial inclusion.

SCSS – 7.9 % for Senior Citizens

SCSS, a five‑year scheme for individuals aged 60 + , retains its 7.9 % rate, reinforcing the safety net for retirees.

Indian Ministry of Finance press briefing Delhi Indian Ministry of Finance press briefing Delhi

The announcement has sparked a surge in searches for “ब्याज” (interest) on Google Trends India, crossing the 2,000‑search threshold within hours. Several factors fuel this spike:

  • High‑stakes decision: Small‑saving rates directly affect millions of depositors.
  • Market timing: Investors are recalibrating portfolios ahead of the upcoming budget.
  • Media amplification: Leading outlets like Aaj Tak, IndiaTimes and Dainik Bhaskar ran front‑page stories, amplifying public curiosity.

“The revised rates are designed to keep small savers incentivised while maintaining fiscal prudence,” – Finance Minister Jitendra Singh (press conference, 30 Sept 2026).

Historical Context of Small‑Saving Schemes

Since the 1950s, the Indian government has used small‑saving schemes to channel household savings into public debt, stabilising the fiscal balance. Over the past decade, rates have trended downwards, mirroring global low‑interest environments. The recent upward tick reflects:

  • Improved fiscal space after a surplus in the 2025‑26 financial year.
  • Rising inflation expectations, prompting the RBI to tighten monetary policy, which in turn nudges government rates upward.
  • Policy intent to boost female‑focused savings, evident in the premium SSY rate.

Impact on Investors and the Economy

For Retail Depositors

  • Higher returns: The uplift translates to an extra ₹1,200 per ₹100,000 invested annually in PPF.
  • Liquidity considerations: While PPF remains locked for 15 years, SCSS offers quarterly interest payouts, appealing to retirees.

For the Government

  • Cost of borrowing: The marginal rise increases the interest burden on the sovereign debt portfolio, but the impact is modest given the limited size of these schemes relative to total debt.
  • Fiscal signaling: A stable or rising rate signals confidence in macroeconomic stability, potentially attracting foreign portfolio inflows.

For the Broader Economy

  • Consumption boost: Higher interest income can spur household spending, especially among retirees.
  • Savings‑investment channel: By keeping small‑savers within the formal financial system, the government ensures a steady flow of low‑cost funds for infrastructure projects.

Key Takeaways

  • PPF at 7.1 %, SSY at 8.2 %, SCSS at 7.9 % – rates are locked for the next fiscal year.
  • The announcement triggered a Google Trends surge due to its direct impact on millions of Indians.
  • Historical context shows a strategic shift toward higher rates after a period of low‑interest policies.
  • Investors should reassess allocation to small‑saving schemes, especially if seeking tax‑benefits and stable returns.
  • The move may bolster consumer confidence and modestly increase the government’s borrowing cost, but overall fiscal health remains strong.

Stay tuned for our next deep‑dive on how these rates compare with bank fixed deposits and the emerging trend of digital‑only savings platforms.


Original Reporting & Source: Google Trends (India)