Umang Sisodia • • 5 min read • 1 view

BPCIL Cuts Corn‑Based Ethanol Prices, Excludes Sugarcane Ethanol – What It Means for India’s Sugar & Energy Sectors

Listen to Article
Select a voice and press play
BPCIL Cuts Corn‑Based Ethanol Prices, Excludes Sugarcane Ethanol – What It Means for India’s Sugar & Energy Sectors

Key Takeaways

  • BPCIL slashes the price of corn‑based ethanol to boost tender participation, while sugarcane‑derived ethanol is omitted from the current procurement round.
  • The move triggers a sharp 7% tumble in select sugar‑linked stocks, reflecting investor anxiety over reduced demand for sugarcane‑based bio‑fuel.
  • Sugar mills are scrambling to diversify into higher‑value bio‑products as traditional ethanol contracts dry up.
  • Long‑term, the decision could reshape India’s ethanol‑sugar nexus, prompting policy tweaks and a re‑evaluation of the country’s renewable fuel roadmap.

Background of India's Ethanol Programme

India’s ambitious Ethanol Blending Programme (EBP) aims to replace 20% of gasoline with ethanol by 2025. The bulk of the feedstock has historically been sugarcane, a crop that also fuels the nation’s massive sugar industry. Over the past few years, however, the government has encouraged corn‑based ethanol to diversify supply, reduce pressure on sugarcane, and stabilize prices.

The Bharat Petroleum Corporation Limited (BPCL), one of the country’s largest fuel marketers, is a key tender‑issuing agency for ethanol procurement. Its pricing decisions directly influence the economics of both corn growers and sugar mills.

BPCIL’s Pricing Decision: What Changed?

On 20 Oct 2026, BPCL announced a 15% reduction in the base price for corn‑derived ethanol, bringing the cost down to ₹ 65 per litre (previously ₹ 77). Simultaneously, the tender document explicitly excluded ethanol produced from sugarcane.

"The revised pricing is intended to enhance competitiveness and attract a broader set of agribusiness participants, while ensuring fuel‑grade quality for our blending program," a BPCL spokesperson said in a press briefing.

Why the Cut?

  1. Global corn price dip – A bumper harvest in the United States and Brazil pushed global corn futures below $ 3 per bushel, making corn‑based ethanol cheaper to produce.
  2. Domestic supply‑demand mismatch – Recent monsoon variability reduced sugarcane yields, tightening the supply of traditional ethanol and prompting the government to look for alternatives.
  3. Policy push for diversification – The Ministry of Petroleum & Natural Gas has repeatedly urged fuel marketers to source ethanol from multiple feedstocks to avoid over‑reliance on sugarcane.

Market Reaction: Stocks, Sugar Prices & Investor Sentiment

The announcement sent ripples across Indian equity markets. Shares of Bajaj Hindusthan Sugar, Balrampur Chini, and Triveni Turbine fell 7‑9% within hours, the steepest decline for any sugar‑linked stock in the past month. Analysts attribute the sell‑off to:

  • Anticipated revenue loss from the exclusion of sugarcane ethanol.
  • Potential over‑stocking of raw sugar, which could depress farm‑gate prices.
  • Uncertainty about future tender structures, as investors fear repeated exclusions.
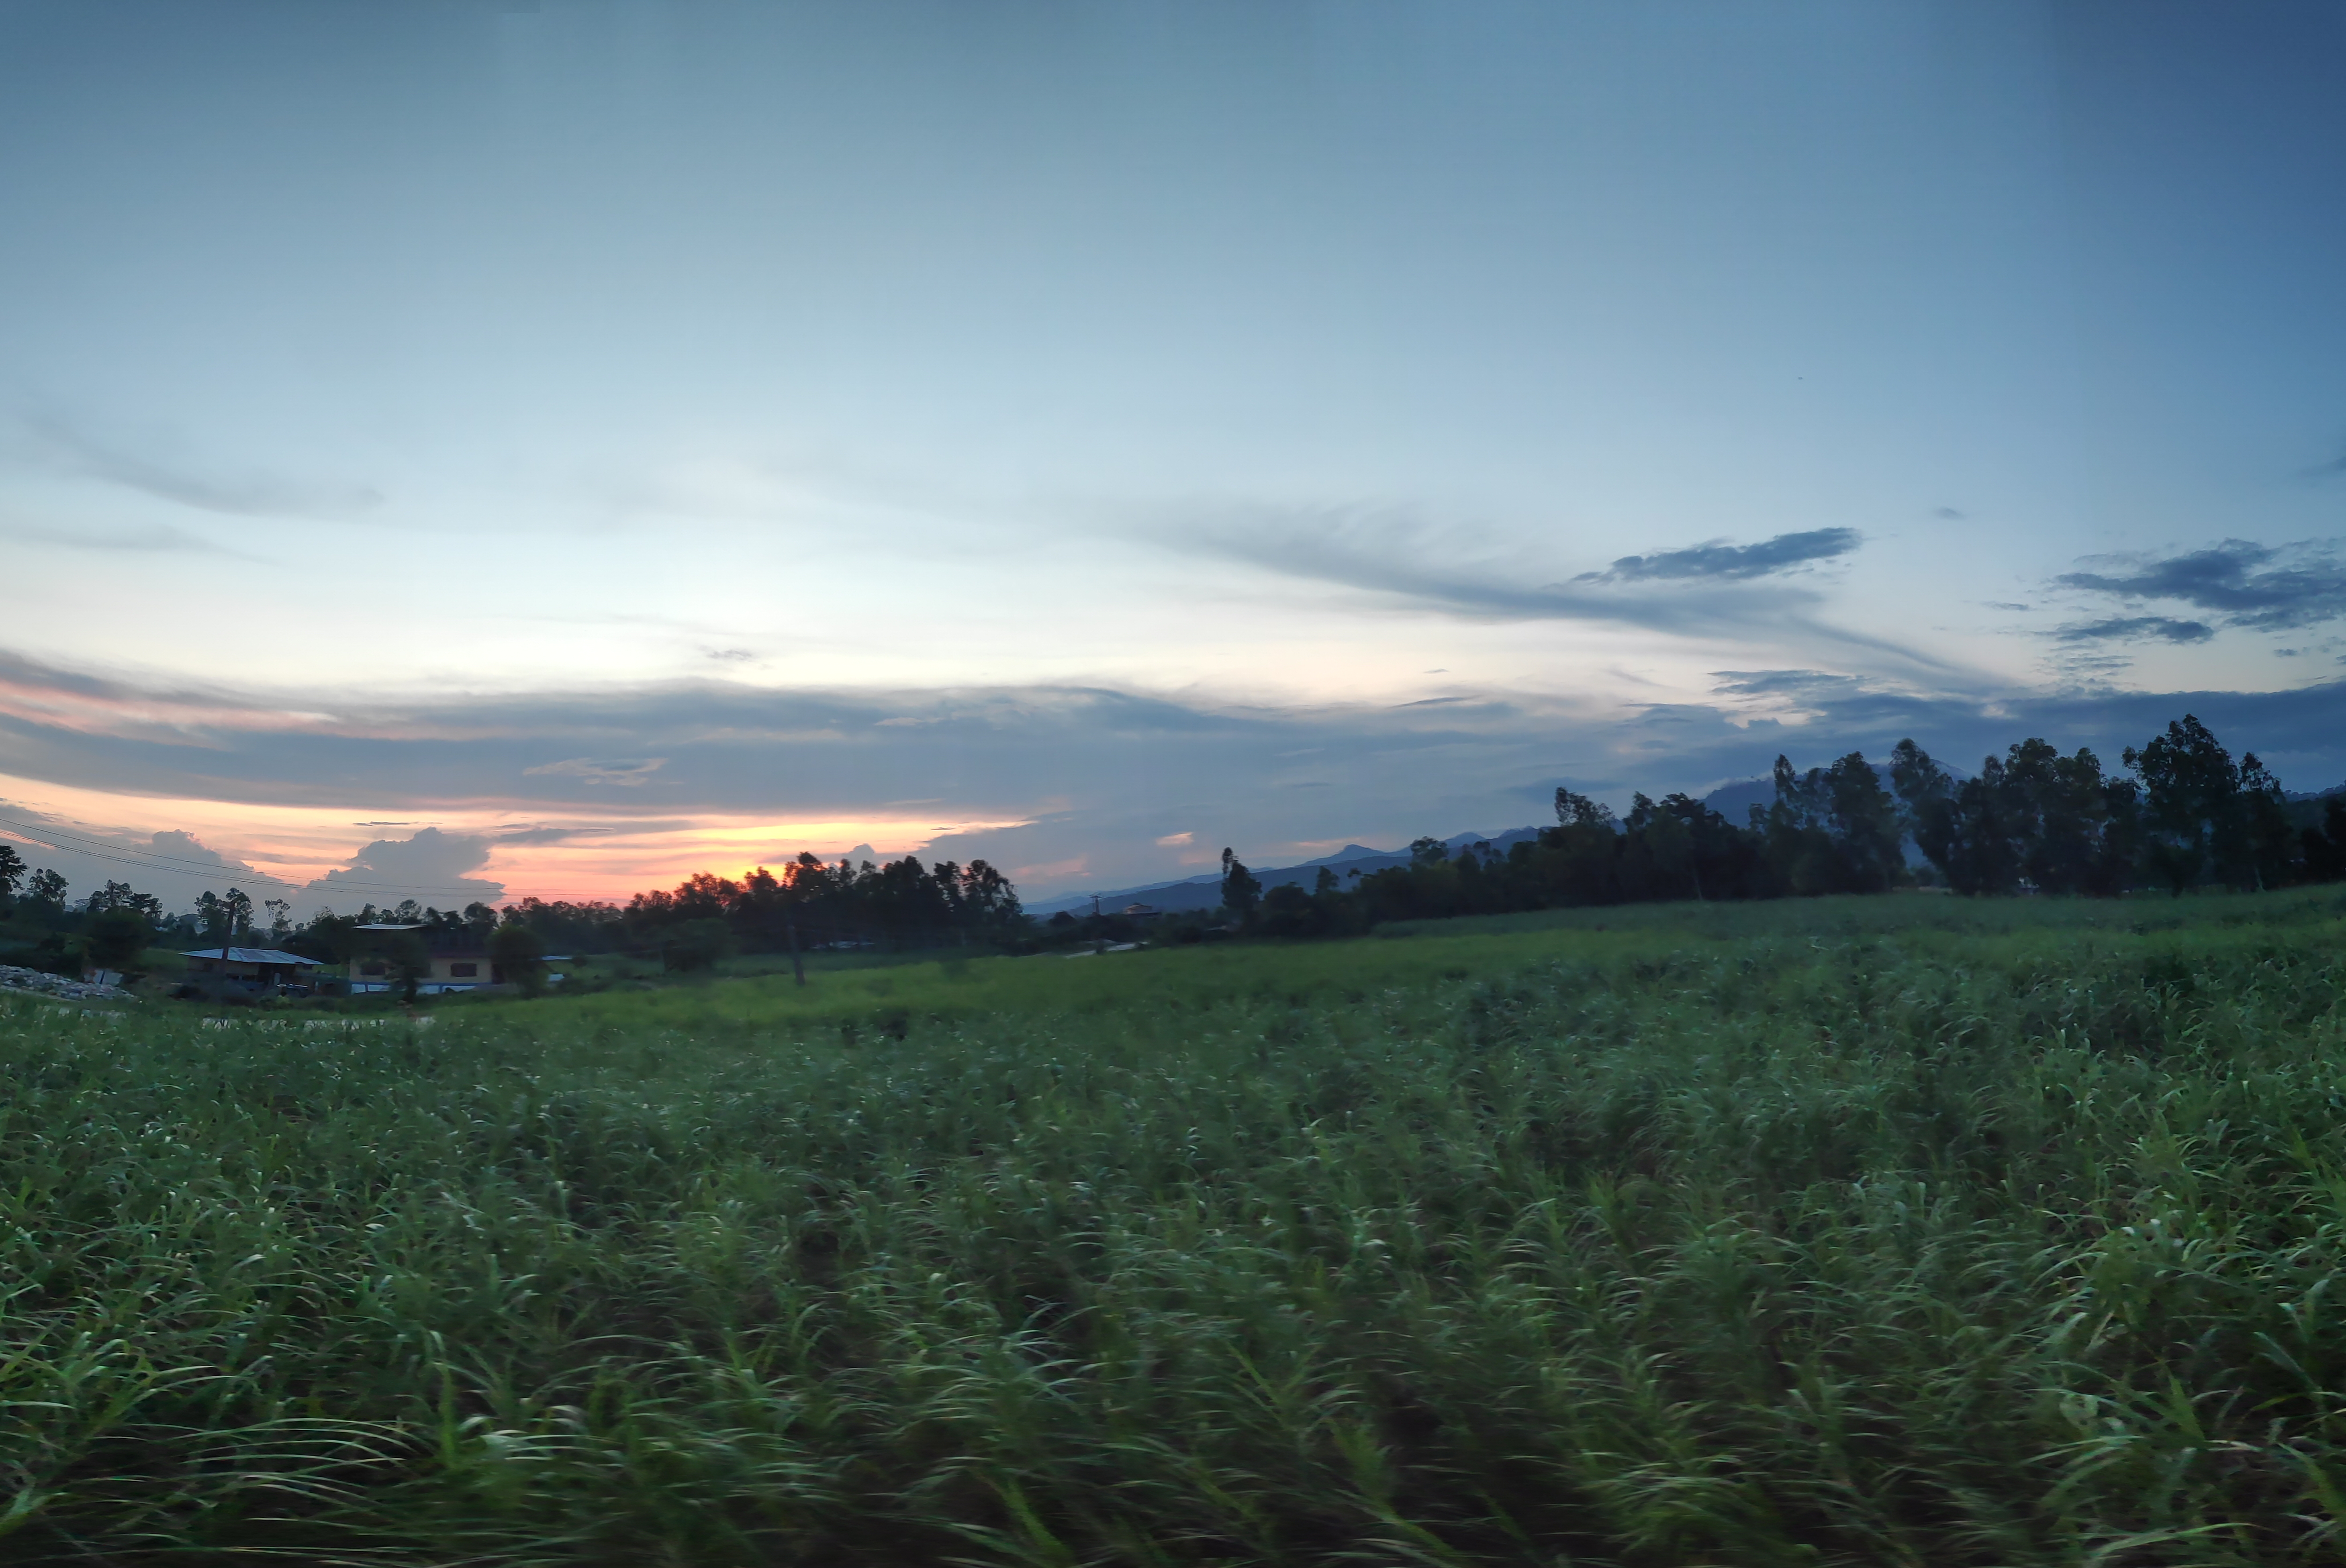
sugarcane field sunset sugarcane field sunset

Implications for the Sugar Industry

Immediate Concerns

  • Revenue Gap – Sugar mills traditionally earn a premium on ethanol sales (≈₹ 30‑40 per litre) compared to raw sugar. Removing this revenue stream tightens profit margins.
  • Operational Realignment – Plants may need to re‑tool to produce alternative bio‑products such as bio‑based polymers, organic acids, or high‑fructose syrups.

Strategic Shifts

  • Diversification into value‑added products – Several mills, as reported by Jagran, are already piloting bio‑based solvents and biodegradable plastics to offset the ethanol shortfall.
  • Exploring alternative feedstocks – Some sugarcane growers are experimenting with sweet sorghum and waste‑to‑energy projects to stay relevant in the bio‑fuel ecosystem.

Government Policy Context

The Ministry of Petroleum & Natural Gas (MoPNG) has set a target of 20% ethanol blending by 2025, but the annual procurement quota is split 70% corn‑based and 30% sugarcane‑based for the 2026‑27 cycle. BPCL’s tender reflects this policy tilt.

Critics argue that excluding sugarcane ethanol undermines the sugar sector’s sustainability, especially when global sugar prices are already volatile. The Ministry, however, maintains that price parity across feedstocks is essential to keep the blending program economically viable.

Broader Energy & Climate Implications

  • Carbon Footprint – Corn‑based ethanol generally has a higher lifecycle emission than sugarcane ethanol due to fertilizer intensity, raising questions about the net climate benefit.
  • Food‑Fuel Balance – A shift toward corn could impact food security, as corn is a staple grain for both human consumption and livestock feed.
  • Renewable Fuel Credibility – Consistency in tender policies is crucial for long‑term investor confidence in India’s renewable fuel market.

Editorial Analysis & Future Outlook

The BPCL price cut is a double‑edged sword. On one hand, it injects much‑needed competition into the ethanol market, encouraging agribusiness diversification and potentially lowering fuel costs for consumers. On the other, it exposes the sugar industry’s structural vulnerability—a sector that has long relied on ethanol contracts to cushion against volatile sugar prices.

If the current trajectory continues, we can expect:

  1. Accelerated R&D in sugar mills for non‑ethanol bio‑products, turning waste streams into high‑value chemicals.
  2. Policy recalibration where the government may introduce minimum procurement quotas for sugarcane ethanol to safeguard farmer incomes and rural employment.
  3. Increased private‑sector participation in corn‑based ethanol, possibly attracting foreign investors keen on leveraging India’s large fuel market.
  4. Regulatory focus on lifecycle emissions, prompting stricter sustainability criteria for all ethanol feedstocks.

In the medium term, the Ethanol Blending Programme’s success will hinge on balanced feedstock sourcing—ensuring that neither corn nor sugarcane is disproportionately favoured. Stakeholders across the value chain—farmers, mill owners, fuel marketers, and policymakers—must collaborate to build a resilient, climate‑smart bio‑fuel ecosystem that supports India’s energy security without compromising agricultural stability.


The author is a senior editor and photojournalist with extensive experience covering India’s energy and agribusiness sectors.


Original Reporting & Source: Google Trends (India)
Discussion (0)

Sign in to join the discussion.

No comments yet. Be the first to start the conversation!

| |

BPCIL Cuts Corn‑Based Ethanol Prices, Excludes Sugarcane Ethanol – What It Means for India’s Sugar & Energy Sectors

By Umang Sisodia • 5 min read • 1 view

Key Takeaways

  • BPCIL slashes the price of corn‑based ethanol to boost tender participation, while sugarcane‑derived ethanol is omitted from the current procurement round.
  • The move triggers a sharp 7% tumble in select sugar‑linked stocks, reflecting investor anxiety over reduced demand for sugarcane‑based bio‑fuel.
  • Sugar mills are scrambling to diversify into higher‑value bio‑products as traditional ethanol contracts dry up.
  • Long‑term, the decision could reshape India’s ethanol‑sugar nexus, prompting policy tweaks and a re‑evaluation of the country’s renewable fuel roadmap.

Background of India's Ethanol Programme

India’s ambitious Ethanol Blending Programme (EBP) aims to replace 20% of gasoline with ethanol by 2025. The bulk of the feedstock has historically been sugarcane, a crop that also fuels the nation’s massive sugar industry. Over the past few years, however, the government has encouraged corn‑based ethanol to diversify supply, reduce pressure on sugarcane, and stabilize prices.

The Bharat Petroleum Corporation Limited (BPCL), one of the country’s largest fuel marketers, is a key tender‑issuing agency for ethanol procurement. Its pricing decisions directly influence the economics of both corn growers and sugar mills.

BPCIL’s Pricing Decision: What Changed?

On 20 Oct 2026, BPCL announced a 15% reduction in the base price for corn‑derived ethanol, bringing the cost down to ₹ 65 per litre (previously ₹ 77). Simultaneously, the tender document explicitly excluded ethanol produced from sugarcane.

"The revised pricing is intended to enhance competitiveness and attract a broader set of agribusiness participants, while ensuring fuel‑grade quality for our blending program," a BPCL spokesperson said in a press briefing.

Why the Cut?

  1. Global corn price dip – A bumper harvest in the United States and Brazil pushed global corn futures below $ 3 per bushel, making corn‑based ethanol cheaper to produce.
  2. Domestic supply‑demand mismatch – Recent monsoon variability reduced sugarcane yields, tightening the supply of traditional ethanol and prompting the government to look for alternatives.
  3. Policy push for diversification – The Ministry of Petroleum & Natural Gas has repeatedly urged fuel marketers to source ethanol from multiple feedstocks to avoid over‑reliance on sugarcane.

Market Reaction: Stocks, Sugar Prices & Investor Sentiment

The announcement sent ripples across Indian equity markets. Shares of Bajaj Hindusthan Sugar, Balrampur Chini, and Triveni Turbine fell 7‑9% within hours, the steepest decline for any sugar‑linked stock in the past month. Analysts attribute the sell‑off to:

  • Anticipated revenue loss from the exclusion of sugarcane ethanol.
  • Potential over‑stocking of raw sugar, which could depress farm‑gate prices.
  • Uncertainty about future tender structures, as investors fear repeated exclusions.

sugarcane field sunset sugarcane field sunset

Implications for the Sugar Industry

Immediate Concerns

  • Revenue Gap – Sugar mills traditionally earn a premium on ethanol sales (≈₹ 30‑40 per litre) compared to raw sugar. Removing this revenue stream tightens profit margins.
  • Operational Realignment – Plants may need to re‑tool to produce alternative bio‑products such as bio‑based polymers, organic acids, or high‑fructose syrups.

Strategic Shifts

  • Diversification into value‑added products – Several mills, as reported by Jagran, are already piloting bio‑based solvents and biodegradable plastics to offset the ethanol shortfall.
  • Exploring alternative feedstocks – Some sugarcane growers are experimenting with sweet sorghum and waste‑to‑energy projects to stay relevant in the bio‑fuel ecosystem.

Government Policy Context

The Ministry of Petroleum & Natural Gas (MoPNG) has set a target of 20% ethanol blending by 2025, but the annual procurement quota is split 70% corn‑based and 30% sugarcane‑based for the 2026‑27 cycle. BPCL’s tender reflects this policy tilt.

Critics argue that excluding sugarcane ethanol undermines the sugar sector’s sustainability, especially when global sugar prices are already volatile. The Ministry, however, maintains that price parity across feedstocks is essential to keep the blending program economically viable.

Broader Energy & Climate Implications

  • Carbon Footprint – Corn‑based ethanol generally has a higher lifecycle emission than sugarcane ethanol due to fertilizer intensity, raising questions about the net climate benefit.
  • Food‑Fuel Balance – A shift toward corn could impact food security, as corn is a staple grain for both human consumption and livestock feed.
  • Renewable Fuel Credibility – Consistency in tender policies is crucial for long‑term investor confidence in India’s renewable fuel market.

Editorial Analysis & Future Outlook

The BPCL price cut is a double‑edged sword. On one hand, it injects much‑needed competition into the ethanol market, encouraging agribusiness diversification and potentially lowering fuel costs for consumers. On the other, it exposes the sugar industry’s structural vulnerability—a sector that has long relied on ethanol contracts to cushion against volatile sugar prices.

If the current trajectory continues, we can expect:

  1. Accelerated R&D in sugar mills for non‑ethanol bio‑products, turning waste streams into high‑value chemicals.
  2. Policy recalibration where the government may introduce minimum procurement quotas for sugarcane ethanol to safeguard farmer incomes and rural employment.
  3. Increased private‑sector participation in corn‑based ethanol, possibly attracting foreign investors keen on leveraging India’s large fuel market.
  4. Regulatory focus on lifecycle emissions, prompting stricter sustainability criteria for all ethanol feedstocks.

In the medium term, the Ethanol Blending Programme’s success will hinge on balanced feedstock sourcing—ensuring that neither corn nor sugarcane is disproportionately favoured. Stakeholders across the value chain—farmers, mill owners, fuel marketers, and policymakers—must collaborate to build a resilient, climate‑smart bio‑fuel ecosystem that supports India’s energy security without compromising agricultural stability.


The author is a senior editor and photojournalist with extensive experience covering India’s energy and agribusiness sectors.


Original Reporting & Source: Google Trends (India)