Umang Sisodia • • 5 min read • 5 views

Fed Holds Rates Steady in Split Vote: What It Means for Inflation and Markets
Listen to Article
Select a voice and press play
Fed Holds Rates Steady in Split Vote: What It Means for Inflation and Markets

Key Takeaways

  • The Federal Reserve voted 7‑2 to keep the policy rate unchanged, marking a split decision amid persistent inflation pressures.
  • Core inflation remains above the 2% target, prompting hawkish members to warn of future tightening.
  • Equity markets reacted positively in the short term, but bond yields edged higher as investors price in lingering rate‑risk.
  • The split underscores growing dissent within the Fed, hinting at a more cautious policy path ahead.

The Decision Explained

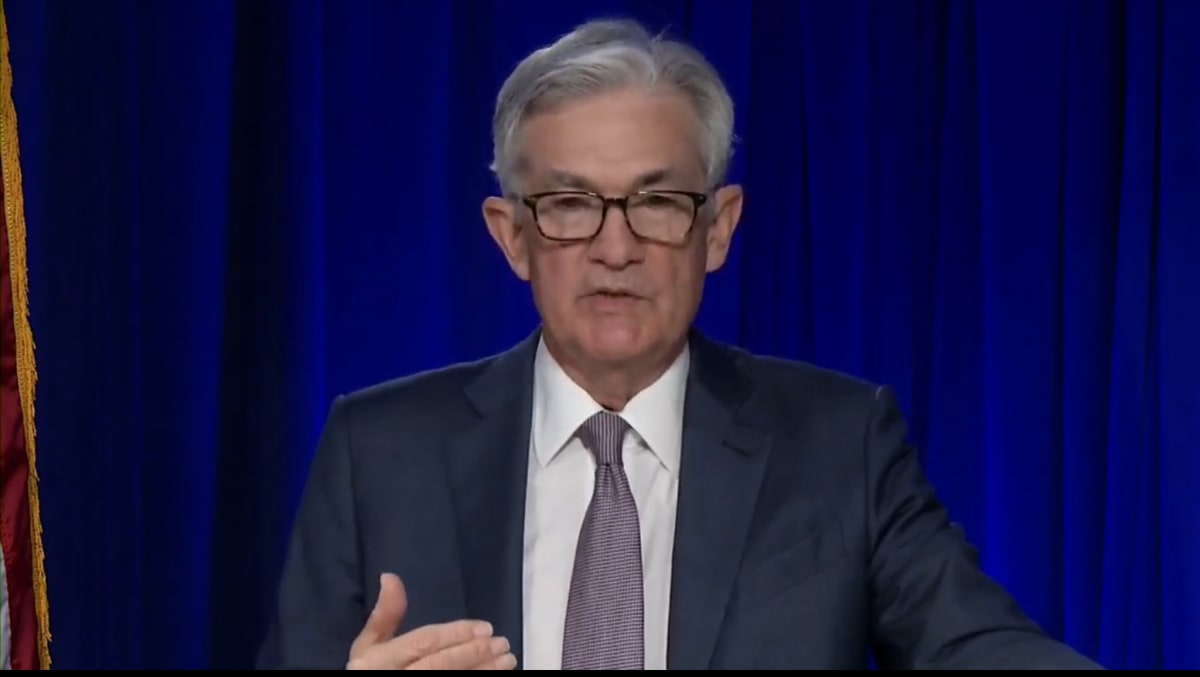
On September 20, 2024, the Federal Open Market Committee (FOMC) concluded its two‑day policy meeting with a 7‑2 vote to hold the federal funds rate steady at the 5.25%‑5.50% range. While the majority opted for patience, two members—Governor Lisa Cook and Vice Chair Philip Jefferson—voted to raise rates by a quarter point.

"We cannot afford to let inflation become entrenched," Governor Cook said in the post‑meeting press conference, emphasizing that "the data still shows price pressures that are too high for comfort."

The split was driven by divergent readings of the latest inflation data. The Consumer Price Index (CPI) showed a year‑over‑year increase of 3.6%, and the core CPI—which strips out food and energy—remained at 4.1%, well above the Fed’s 2% target. While the overall headline inflation has cooled from its 2022 peak, the sticky core component continues to fuel concerns among the more hawkish members.

Why Inflation Remains Sticky

Several structural factors are keeping inflation elevated:

  1. Labor market tightness – Unemployment sits at a historic low of 3.4%, giving workers leverage to demand higher wages, which in turn feeds into price hikes.
  2. Supply‑chain bottlenecks – Although global shipping has improved, semiconductor shortages and logistics constraints still cause price spikes in tech and automotive sectors.
  3. Energy price volatility – Geopolitical tensions in the Middle East have kept oil prices volatile, spilling over into transportation and manufacturing costs.
  4. Rising rents – Housing costs have surged in major metros, contributing significantly to the core inflation metric.

These elements create a feedback loop: higher wages raise consumer purchasing power, which sustains demand‑driven price increases, prompting the Fed to consider further tightening.

Market Reaction and Investor Sentiment

The immediate market response was a classic "Fed hold" rally. The S&P 500 jumped 1.2% on the day, while the Nasdaq outperformed with a 1.5% gain. However, the bond market told a more nuanced story. The 10‑year Treasury yield edged up to 4.38%, reflecting investors’ anticipation of potential future hikes if inflation does not recede.

"The equity rally is a relief, but the bond market remains wary," noted senior analyst Maya Patel of Morgan Stanley. "Investors are pricing in a scenario where the Fed might resume tightening later this year."

Sector‑wise, financials benefited from higher rate expectations, while consumer discretionary and real‑estate stocks showed mixed performance, wary of sustained price pressures.
Wall Street traders reacting to Fed decision Wall Street traders reacting to Fed decision

Political and Global Implications

The split decision reverberates beyond Wall Street. Congressional leaders have been pressing the Fed for clearer guidance on the path forward, fearing that prolonged high rates could slow economic growth and increase fiscal deficits. Meanwhile, international markets are watching closely. Emerging economies with dollar‑denominated debt are vulnerable to any shift in U.S. rates, and a prolonged high‑rate environment could exacerbate capital outflows.

In Europe, the European Central Bank (ECB) is also navigating a similar inflation dilemma, and the Fed’s stance often sets a benchmark for global monetary policy. Analysts suggest that a coordinated pause among major central banks could help stabilize global commodity prices and exchange rates.

Editorial Analysis & Future Outlook

The Fed’s split vote is more than a procedural footnote; it signals a deepening ideological divide within the Committee. While the majority leans toward a data‑dependent, patient approach, the dissenting voices are warning that inflation’s core components are entrenched and could require additional tightening.

What to watch next:

  • Upcoming CPI releases (especially core CPI) – Any upward surprise could tip the balance toward a rate hike at the next meeting in November.
  • Labor market reports – A continued low unemployment rate may embolden hawks.
  • Geopolitical developments – Escalations that affect oil supply could reignite inflation spikes.
  • Fed communications – The language in the Summary of Economic Projections (SEP) will be a key indicator of the Committee’s future bias.

For investors, the prudent strategy remains diversification and risk management. Equities may enjoy short‑term upside, but duration‑sensitive bonds could face volatility if the Fed signals a shift. Real‑asset allocations (like commodities and inflation‑protected securities) may also serve as a hedge against persistent price pressures.

In the long run, the Fed’s ability to anchor inflation expectations will determine whether the U.S. economy can sustain growth without resorting to aggressive rate hikes. The current split decision underscores that the path ahead is uncertain, and both policymakers and market participants must stay vigilant.


Stay tuned for our deep‑dive coverage of the Fed’s next meeting and its ripple effects across global markets.


Original Reporting & Source: Yahoo Finance
Discussion (0)

Sign in to join the discussion.

No comments yet. Be the first to start the conversation!

| |

Fed Holds Rates Steady in Split Vote: What It Means for Inflation and Markets

By Umang Sisodia • 5 min read • 5 views

Key Takeaways

  • The Federal Reserve voted 7‑2 to keep the policy rate unchanged, marking a split decision amid persistent inflation pressures.
  • Core inflation remains above the 2% target, prompting hawkish members to warn of future tightening.
  • Equity markets reacted positively in the short term, but bond yields edged higher as investors price in lingering rate‑risk.
  • The split underscores growing dissent within the Fed, hinting at a more cautious policy path ahead.

The Decision Explained

On September 20, 2024, the Federal Open Market Committee (FOMC) concluded its two‑day policy meeting with a 7‑2 vote to hold the federal funds rate steady at the 5.25%‑5.50% range. While the majority opted for patience, two members—Governor Lisa Cook and Vice Chair Philip Jefferson—voted to raise rates by a quarter point.

"We cannot afford to let inflation become entrenched," Governor Cook said in the post‑meeting press conference, emphasizing that "the data still shows price pressures that are too high for comfort."

The split was driven by divergent readings of the latest inflation data. The Consumer Price Index (CPI) showed a year‑over‑year increase of 3.6%, and the core CPI—which strips out food and energy—remained at 4.1%, well above the Fed’s 2% target. While the overall headline inflation has cooled from its 2022 peak, the sticky core component continues to fuel concerns among the more hawkish members.

Why Inflation Remains Sticky

Several structural factors are keeping inflation elevated:

  1. Labor market tightness – Unemployment sits at a historic low of 3.4%, giving workers leverage to demand higher wages, which in turn feeds into price hikes.
  2. Supply‑chain bottlenecks – Although global shipping has improved, semiconductor shortages and logistics constraints still cause price spikes in tech and automotive sectors.
  3. Energy price volatility – Geopolitical tensions in the Middle East have kept oil prices volatile, spilling over into transportation and manufacturing costs.
  4. Rising rents – Housing costs have surged in major metros, contributing significantly to the core inflation metric.

These elements create a feedback loop: higher wages raise consumer purchasing power, which sustains demand‑driven price increases, prompting the Fed to consider further tightening.

Market Reaction and Investor Sentiment

The immediate market response was a classic "Fed hold" rally. The S&P 500 jumped 1.2% on the day, while the Nasdaq outperformed with a 1.5% gain. However, the bond market told a more nuanced story. The 10‑year Treasury yield edged up to 4.38%, reflecting investors’ anticipation of potential future hikes if inflation does not recede.

"The equity rally is a relief, but the bond market remains wary," noted senior analyst Maya Patel of Morgan Stanley. "Investors are pricing in a scenario where the Fed might resume tightening later this year."

Sector‑wise, financials benefited from higher rate expectations, while consumer discretionary and real‑estate stocks showed mixed performance, wary of sustained price pressures.

Wall Street traders reacting to Fed decision Wall Street traders reacting to Fed decision

Political and Global Implications

The split decision reverberates beyond Wall Street. Congressional leaders have been pressing the Fed for clearer guidance on the path forward, fearing that prolonged high rates could slow economic growth and increase fiscal deficits. Meanwhile, international markets are watching closely. Emerging economies with dollar‑denominated debt are vulnerable to any shift in U.S. rates, and a prolonged high‑rate environment could exacerbate capital outflows.

In Europe, the European Central Bank (ECB) is also navigating a similar inflation dilemma, and the Fed’s stance often sets a benchmark for global monetary policy. Analysts suggest that a coordinated pause among major central banks could help stabilize global commodity prices and exchange rates.

Editorial Analysis & Future Outlook

The Fed’s split vote is more than a procedural footnote; it signals a deepening ideological divide within the Committee. While the majority leans toward a data‑dependent, patient approach, the dissenting voices are warning that inflation’s core components are entrenched and could require additional tightening.

What to watch next:

  • Upcoming CPI releases (especially core CPI) – Any upward surprise could tip the balance toward a rate hike at the next meeting in November.
  • Labor market reports – A continued low unemployment rate may embolden hawks.
  • Geopolitical developments – Escalations that affect oil supply could reignite inflation spikes.
  • Fed communications – The language in the Summary of Economic Projections (SEP) will be a key indicator of the Committee’s future bias.

For investors, the prudent strategy remains diversification and risk management. Equities may enjoy short‑term upside, but duration‑sensitive bonds could face volatility if the Fed signals a shift. Real‑asset allocations (like commodities and inflation‑protected securities) may also serve as a hedge against persistent price pressures.

In the long run, the Fed’s ability to anchor inflation expectations will determine whether the U.S. economy can sustain growth without resorting to aggressive rate hikes. The current split decision underscores that the path ahead is uncertain, and both policymakers and market participants must stay vigilant.


Stay tuned for our deep‑dive coverage of the Fed’s next meeting and its ripple effects across global markets.


Original Reporting & Source: Yahoo Finance