Umang Sisodia • • 6 min read • 1 view
RBI Floats Higher: How the New Floating‑Rate Bond Can Boost Safe Returns for Indian Investors
Key Takeaways
- RBI’s latest floating‑rate bond (FRB) hike pushes yields above 8%, making it a top safe‑harbor option for risk‑averse investors.
- A ₹5 lakh investment can generate roughly ₹2.61 lakh interest over five years, outpacing most fixed deposits.
- Senior citizens and retirees stand to gain the most, but the bond’s variable nature requires careful monitoring of policy rates.
- Investing is straightforward: open a demat account, apply through your bank or broker, and hold the bond till maturity or trade on secondary markets.
What Is the RBI Floating‑Rate Bond?
The Reserve Bank of India (RBI) introduced the Floating‑Rate Bond (FRB) in 2022 as a sovereign instrument that adjusts its coupon every six months in line with the prevailing policy repo rate plus a fixed spread. Unlike traditional fixed‑rate bonds, the FRB protects investors from interest‑rate volatility by ensuring that returns rise when the RBI tightens monetary policy and fall when it eases.
"Floating‑rate securities provide a hedge against rising rates while preserving the credit quality of sovereign debt," – RBI Governor Shaktikanta Das (press conference, March 2024).
The bond’s tenure is five years, with semi‑annual coupon resets. The latest RBI policy decision raised the repo rate by 25 basis points, and the FRB’s spread was also nudged upward, pushing the effective yield to **8.60 %**—the highest for any government‑backed retail instrument in the current cycle.
Why the Interest Rate Hike Matters
1. Safe‑Harbor Yield Surge
Fixed deposits (FDs) in Indian banks have been climbing, but the average FD rate for senior citizens caps at around 7.5 % for five‑year tenures. The FRB’s 8.60 % yield not only eclipses this benchmark but also carries the sovereign credit rating of India (AAA‑NR), eliminating bank‑specific credit risk.
2. Inflation‑Adjusted Returns
India’s headline inflation has hovered near 5 % this year. A floating‑rate instrument that tracks policy rates inherently offers a better real‑return profile than a static‑rate FD, especially when the RBI signals further tightening to curb price pressures.
3. Portfolio Diversification
For equity‑heavy portfolios, adding a sovereign FRB reduces overall volatility. Its correlation with stock market indices is low, making it an attractive ballast during market corrections.
How to Invest: Step‑by‑Step Guide
| Step | Action | Details |
|---|---|---|
| 1 | Open a Demat & Trading Account | Most banks and discount brokers (Zerodha, Upstox, Angel One) offer instant e‑KYC onboarding. |
| 2 | Check Eligibility | Indian residents aged 18 +; senior citizens (60 +) enjoy a 0.5 % extra spread. |
| 3 | Place the Order | Log into the trading platform, search for “RBI FRB 2024‑29”, select the desired lot size (₹1 lakh per lot), and submit a buy order. |
| 4 | Settle & Hold | Funds are debited, the bond is credited to your demat account, and coupons are credited semi‑annually to your linked bank account. |
| 5 | Monitor Policy Moves | RBI’s monetary‑policy calendar (usually the first Thursday of every month) will dictate the next coupon reset. |
Minimum Investment
The RBI sets a minimum subscription of ₹1 lakh per investor, with the option to purchase additional lots in multiples of ₹1 lakh. For a typical middle‑class saver, a ₹5 lakh allocation yields a projected ₹2.61 lakh interest over five years, assuming the current 8.60 % yield remains constant.
Where to Buy?
- Bank Branches: Most public‑sector banks (SBI, PNB, Bank of Baroda) have dedicated bond desks.
- Online Platforms: NSE/BSE bond‑trading portals, as well as the RBI’s own e‑Bond portal for retail investors.
- Wealth‑Management Apps: Groww, Paytm Money, and Kuvera now list FRBs alongside mutual funds.
Risks & Considerations
- Rate‑Reset Lag: Coupons are set based on the repo rate six months prior, meaning investors experience a lag in benefit when rates rise sharply.
- Liquidity: While FRBs are listed on secondary markets, trading volumes can be thin, leading to modest price discovery and potential discount if sold before maturity.
- Taxation: Interest income is taxed as per the investor’s slab; senior citizens receive a higher exemption limit, but the overall tax drag can reduce net returns.
Market Reaction to the Recent RBI Move
The RBI’s decision to raise the FRB spread sparked a 2.3 % rally in the bond’s secondary‑market price on the day of the announcement. Retail investors flocked to the instrument, driving up demand for the next tranche slated for issuance in Q4 2024. Analysts at Motilal Oswal and ICICI Direct upgraded their ratings on the FRB, citing its “exceptional risk‑adjusted return profile.”
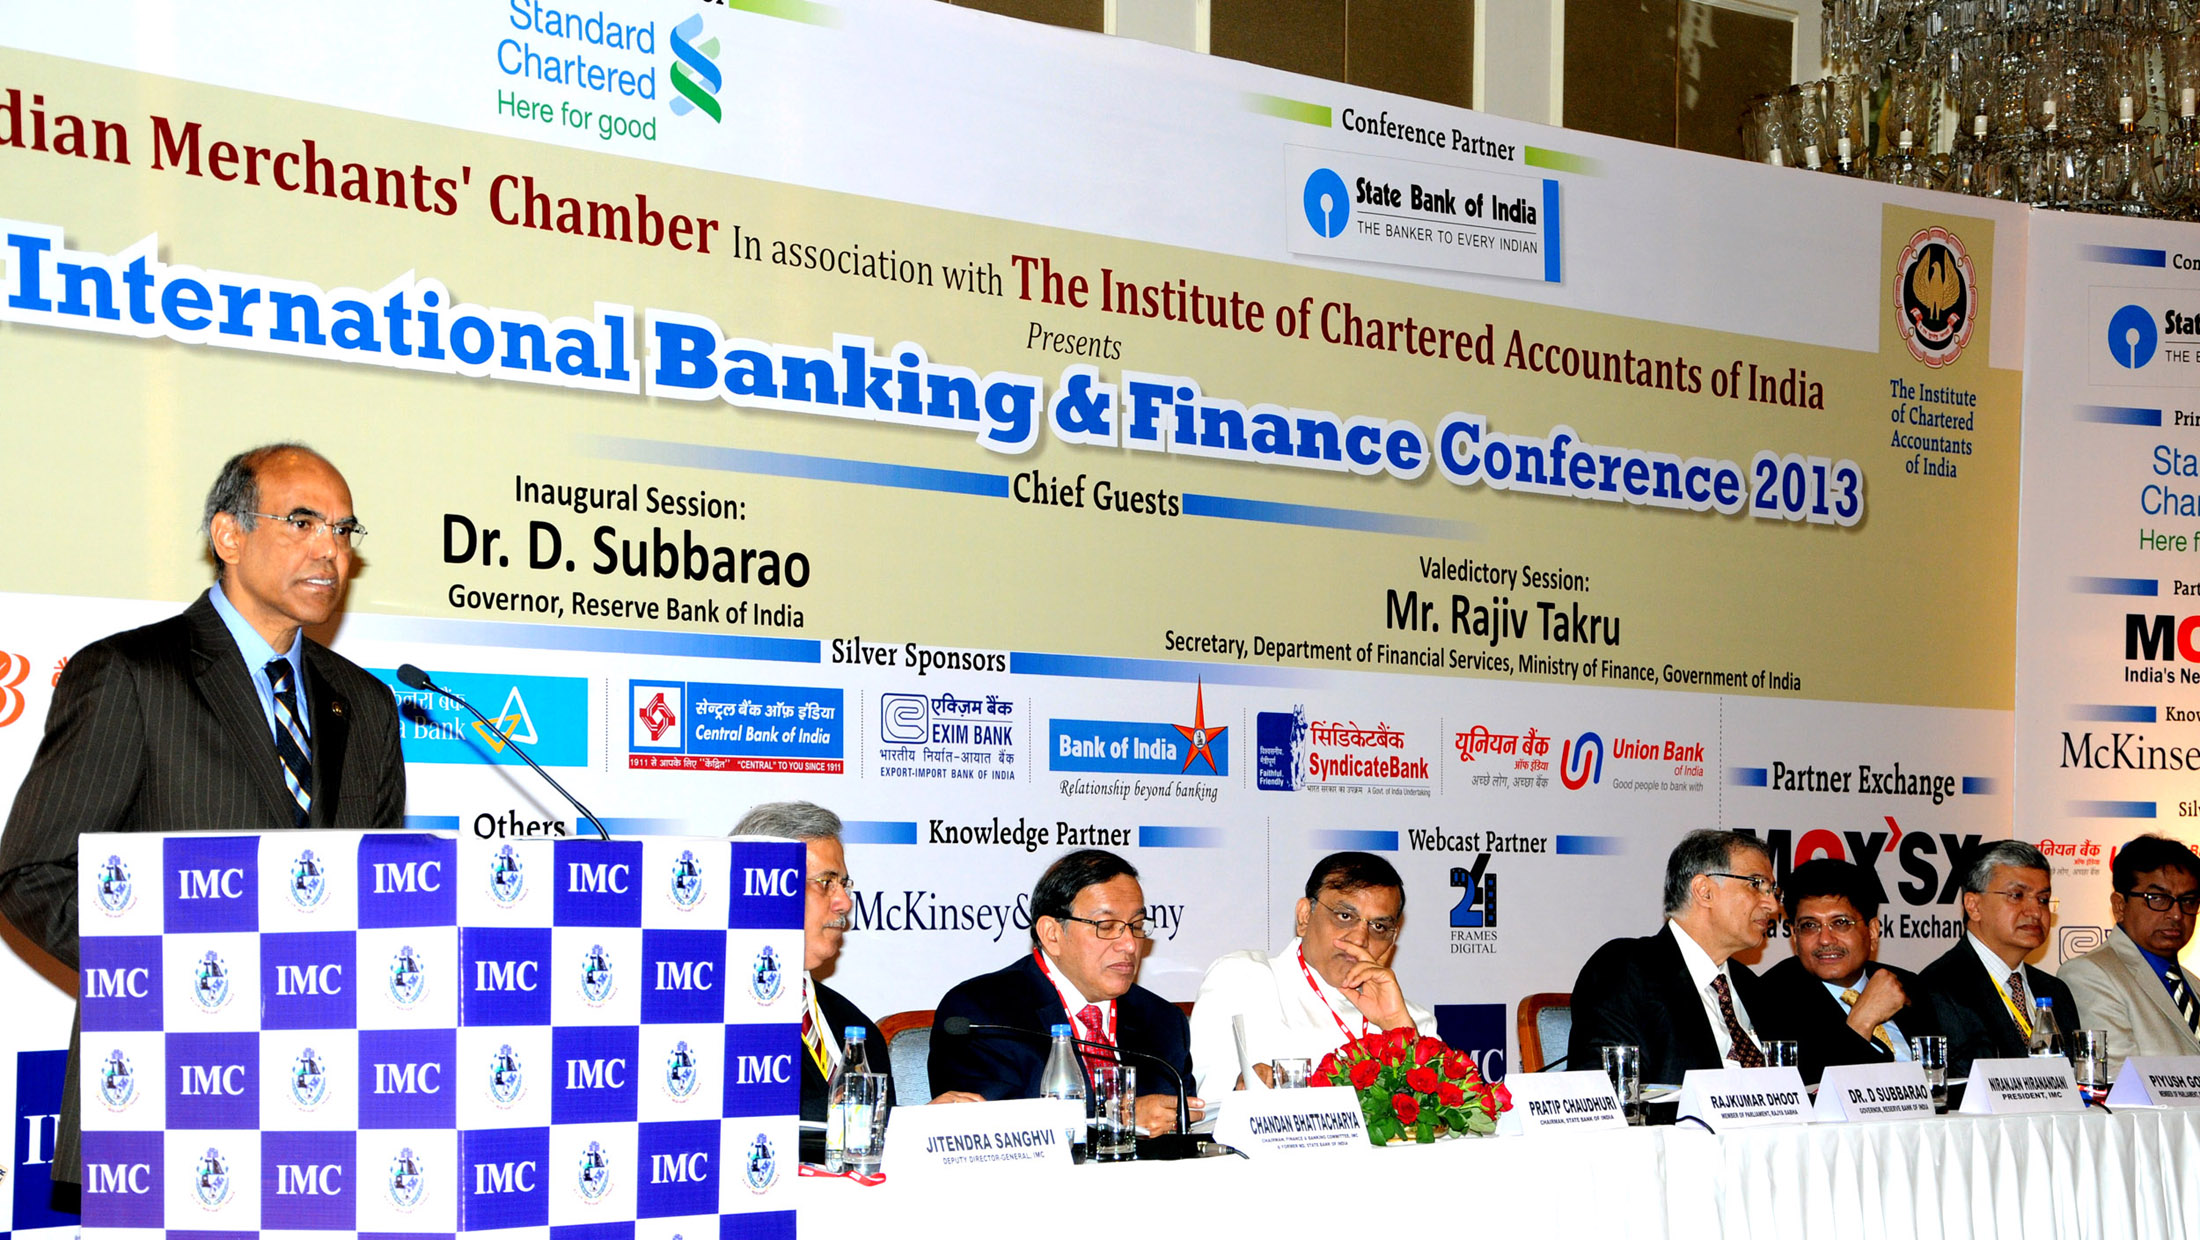 RBI press conference
Comparative Snapshot: FRB vs. Traditional Fixed Deposits
| Feature | RBI Floating‑Rate Bond | Bank Fixed Deposit (Senior Citizen) |
|---|---|---|
| Yield (5‑yr) | 8.60 % (current) | 7.50 % (max) |
| Credit Risk | Sovereign (AAA‑NR) | Bank‑specific (varies) |
| Liquidity | Moderate (secondary market) | Low (premature withdrawal penalties) |
| Tax Treatment | Interest taxed as per slab | Same as FRB |
| Inflation Hedge | Yes (rate‑linked) | No (fixed) |
Frequently Asked Questions (FAQs)
Q1. Can NRIs invest in the RBI FRB? A: Yes, NRIs with a valid PAN and NRE/NRO accounts can subscribe through designated overseas branches or Indian brokers.
Q2. What happens if the repo rate falls? A: Coupon rates will adjust downward at the next reset, reducing future interest but preserving the bond’s principal.
Q3. Is there a lock‑in period? A: No mandatory lock‑in, but early redemption on the secondary market may attract a discount due to lower liquidity.
Editorial Analysis & Future Outlook
The RBI’s decision to boost the floating‑rate bond’s spread is a strategic maneuver aimed at deepening the domestic bond market while offering a sovereign‑backed alternative to bank FDs. In the short term, the move will attract a wave of retail capital, especially from senior citizens seeking higher post‑tax yields amid a tightening monetary stance.
Long‑term, the FRB could become a cornerstone of India’s financial‑inclusion agenda. By channeling household savings into government securities, the RBI reduces reliance on bank deposits, thereby lowering systemic liquidity pressure on commercial banks. Moreover, the semi‑annual reset mechanism aligns investor returns with macro‑policy, creating a self‑sustaining demand loop as future rate hikes automatically enhance bond attractiveness.
However, the success of the FRB hinges on improving secondary‑market liquidity. Policymakers may need to incentivize market makers or introduce a dedicated bond‑exchange platform to ensure price stability for early sellers. Additionally, clearer communication on the reset schedule and spread calculation will mitigate confusion among first‑time retail buyers.
If these operational frictions are addressed, the RBI floating‑rate bond could reshape India’s retail‑investment landscape, positioning sovereign debt as a mainstream, high‑yield, low‑risk asset class—comparable to the U.S. Treasury Inflation‑Protected Securities (TIPS) in the West.
In essence, the current surge is not a fleeting hype but a structural shift toward smarter, policy‑linked savings instruments. Savvy investors who understand the mechanics and monitor RBI policy cues stand to reap significant, inflation‑adjusted gains while contributing to a more resilient national financial system.
Original Reporting & Source: Google Trends (India)
Discussion (0)
Sign in to join the discussion.
No comments yet. Be the first to start the conversation!