Umang Sisodia • • 4 min read • 13 views
MDR on UPI: Why Finance Minister Nirmala Sitharaman Calls It a Tax, Not a Cess
What sparked the debate?
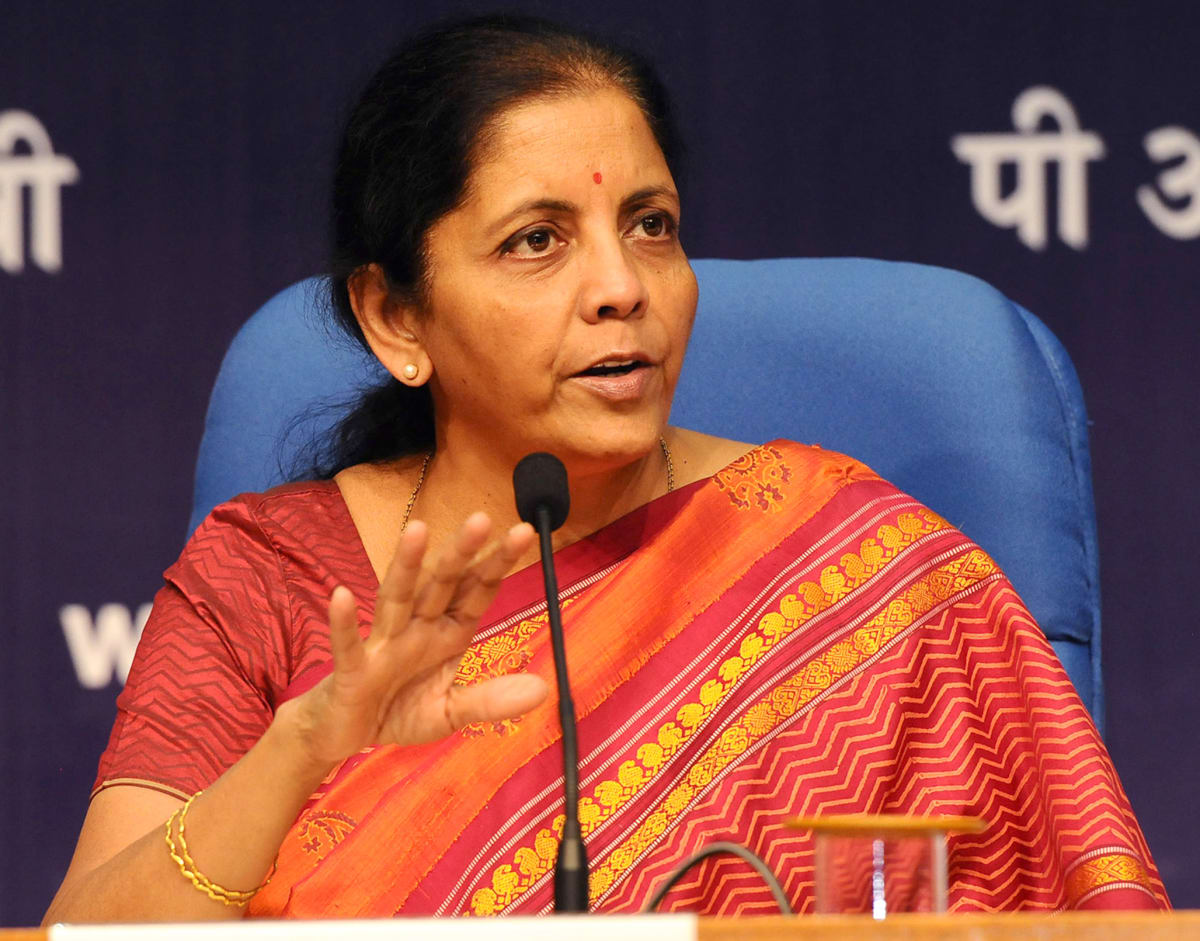
In the last week, the phrase "MDR ట్యాక్సో, సెస్సో కాదు" trended across Google India with more than 500 searches per day. The flashpoint was Finance Minister Nirmala Sitharaman’s statement that the Merchant Discount Rate (MDR) levied on UPI transactions is not a cess – it is a tax that does not flow into the government’s exchequer. The comment was first reported by Eenadu and quickly amplified by regional news portals such as Asianet News Telugu and LatestLY.
Understanding MDR and why it matters
- MDR (Merchant Discount Rate) – a percentage that banks and payment processors charge merchants for each digital transaction. For UPI, the current MDR ceiling is 0.30 % for transactions up to ₹2,000 and 0.40 % beyond that.
- Cess vs. Tax – A cess is a specific levy earmarked for a particular purpose (often health, education, etc.) and is collected by the central government. A tax, on the other hand, can be retained by the entity that imposes it – in this case, the banks.
- GST on UPI – Parallel to the MDR debate, the government announced a 18 % GST on UPI payments that exceed ₹2,000. This has added another layer of confusion for merchants and consumers alike.
"MDR is a tax, not a cess. The government does not receive a rupee from it," – Nirmala Sitharaman
Why the topic is surging on Google Trends
- Consumer anxiety – Small traders fear that a higher MDR or GST will erode thin profit margins, especially in the burgeoning tier‑2 and tier‑3 markets.
- Policy ambiguity – The Finance Ministry’s clarification came after weeks of speculation about whether the ₹2,000 threshold would trigger a new tax regime.
- Media amplification – Regional outlets in Telugu, Tamil, and Hindi have run headline‑grabbing stories, driving search traffic from multiple language groups.
The political backdrop
The MDR discussion is not happening in a vacuum. The Centre is navigating:
- Fiscal consolidation – With the fiscal deficit hovering around 6.5 % of GDP, every revenue source is under scrutiny.
- Digital payments push – India aims for ₹10 trillion in digital transactions by 2026. A steep MDR could stall this ambition.
- State‑center dynamics – Several state governments have lobbied for a share of the MDR proceeds, arguing that the tax‑like nature of MDR should benefit sub‑national bodies.
Potential impact on the ecosystem
| Stakeholder | Immediate Effect | Long‑term Outlook |
|---|---|---|
| Merchants | Higher transaction cost for sales > ₹2,000 | May shift to cash or alternative wallets to avoid GST |
| Banks & PSPs | Retain MDR revenue; can price‑differentiate | Could face regulatory pressure to lower rates |
| Government | No direct revenue from MDR; relies on GST | May explore a direct levy on digital payments in future |
| Consumers | Slight price uptick on high‑value purchases | Possible reduction in UPI usage for big-ticket items |
What experts say
- Raghavendra Rao, fintech analyst: "If the MDR remains a tax, banks will keep the margin, but the government loses a potential revenue stream. The GST on high‑value UPI could be a stop‑gap, yet it may push merchants toward cash, undermining the digital agenda."
- Shreya Patel, small‑business association head: "Our members are already struggling with input‑tax credits. An extra 18 % GST on a transaction over ₹2,000 feels punitive."
The road ahead
The Ministry has promised clarity on the ₹2,000 threshold and hinted at a tiered GST model that could exempt low‑value transactions. Meanwhile, the Reserve Bank of India (RBI) is reviewing the MDR ceiling to ensure it aligns with the "Make in India" digital payments vision.
Stakeholders are watching closely:
- Parliamentary committees may summon the Finance Minister for a detailed briefing.
- State finance ministries could demand a share of MDR proceeds, citing the tax argument.
- Fintech startups are preparing to adapt pricing models if GST expands.
Key takeaways
- MDR is classified as a tax, meaning the government does not receive direct revenue.
- GST of 18 % applies to UPI payments above ₹2,000, adding cost pressure on merchants.
- Policy clarity is still evolving, and the outcome will shape India’s digital payments future.
 UPI payment terminal GST overlay
The conversation around MDR and GST is a litmus test for India’s ability to balance fiscal prudence with a digital‑first economy. As the debate unfolds, merchants, banks, and consumers will all feel the ripple effects of the final policy decision.
Original Reporting & Source: Google Trends (India)
Discussion (0)
Sign in to join the discussion.
No comments yet. Be the first to start the conversation!