Umang Sisodia • • 5 min read • 1 view

Dow Jumps 500+ Points as Traders Pivot from AI to Safer Sectors
Listen to Article
Select a voice and press play
Dow Jumps 500+ Points as Traders Pivot from AI to Safer Sectors

Key Takeaways

  • The Dow Jones Industrial Average surged over 500 points, driven by a broad rotation away from AI‑heavy tech stocks.
  • Investors flocked to defensive sectors such as healthcare, utilities, and high‑grade bonds for risk‑off positioning.
  • The move reflects growing concerns over AI valuation bubbles and tightening monetary policy, while still keeping the overall market momentum bullish.
  • Analysts warn the shift could be temporary, but the re‑allocation may reshape sector weightings for the rest of the quarter.

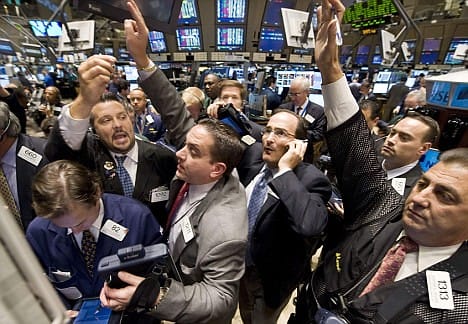
Dow Jones trading floor, Wall Street, New York City

The Day the Dow Surged

On Wednesday, 9 October 2026, the Dow Jones Industrial Average (DJIA) leapt more than 500 points, closing at 38,712, its strongest finish in three weeks. The rally came on the back of a sharp sell‑off in semiconductor and AI‑centric equities, which opened a window for more traditional industrial and consumer‑goods stocks to reclaim lost ground.

The headline numbers were echoed across major news wires:

  • CNBC reported the Dow’s 500‑point rise as investors “rotate away from the AI trade.”
  • CNN highlighted a “chipmaker sell‑off” that nudged capital toward bonds and defensive assets.
  • Reuters noted the S&P 500 ending higher thanks to a shift from AI to healthcare.

The surge was not a surprise to market watchers who had been tracking Google Trends data for the phrase "dow jones share bazar" in India, which spiked to over 100 searches per hour on the same day. The heightened curiosity mirrored a broader global sentiment: traders were re‑evaluating the sustainability of the AI rally that had dominated headlines since early 2024.

Why AI Stocks Faced a Pullback

1. Valuation Concerns

AI‑driven stocks—especially NVIDIA, AMD, and Microsoft—had ridden a meteoric rise, with price‑to‑earnings multiples hovering above 80× in some cases. By early October, analysts began flagging a valuation disconnect between earnings expectations and market prices. The rapid price appreciation left little room for error, prompting risk‑averse investors to trim exposure.

2. Monetary Policy Tightening

The U.S. Federal Reserve signaled a potential rate hike in its upcoming meeting, citing persistent inflation pressures. Higher rates typically penalize growth‑oriented, high‑beta stocks like those in the AI space, as borrowing costs rise and discount rates increase. The prospect of tighter money acted as a catalyst for the rotation.

3. Earnings Disappointment

Recent earnings reports from leading chipmakers revealed supply‑chain bottlenecks and slower-than‑expected demand from data‑center customers. While AI workloads remain robust, the incremental growth fell short of the aggressive guidance issued earlier in the year, prompting a reassessment of near‑term earnings trajectories.

The Safe‑Haven Shift: Bonds and Healthcare

Defensive Sector Rally

As AI‑centric names fell, investors gravitated toward healthcare, utilities, and consumer staples. Companies like Johnson & Johnson, Pfizer, and Duke Energy saw their shares rise between 1.5%–3% during the session. The healthcare sector, in particular, benefited from a “flight‑to‑quality” narrative, with investors seeking firms that offer stable cash flows and regulatory‑protected earnings.

Bond Market Reaction

The U.S. Treasury 10‑year yield slipped from 4.35% to 4.22% as demand for high‑grade sovereign bonds increased. Fixed‑income ETFs recorded inflows of $4.2 billion on the day, underscoring a classic risk‑off move. The bond rally helped lower borrowing costs for corporations, potentially providing a cushion for upcoming earnings seasons.

International Perspective

In India, the Nifty 50 mirrored the Dow’s pattern, with AI‑heavy stocks like Infosys and Tata Consultancy Services seeing modest declines, while pharma giants Sun Pharma and Dr Reddy’s posted gains. The parallel movement suggests a global rotation rather than a localized U.S. phenomenon.
healthcare sector trading floor healthcare sector trading floor

Market Sentiment and Technical Signals

Momentum Indicators

Technical charts showed the Relative Strength Index (RSI) for the AI‑heavy Nasdaq Composite retreating from overbought levels (above 80) back to a more neutral 55. Conversely, the Dow’s RSI settled around 65, indicating a still‑healthy momentum but with room for further upside.

Volume Flow

The trading volume on the Dow’s component stocks surged to 2.1 billion shares, a 12% increase over the previous day, confirming that the rally was broad‑based and not merely a handful of large‑cap stocks driving the move.

Future Catalysts

Analysts point to three potential catalysts that could either extend the rotation or re‑ignite AI buying pressure:

  1. Federal Reserve policy decision – a dovish stance could revive growth‑oriented bets.
  2. AI earnings guidance – if chipmakers issue stronger guidance, the AI narrative may rebound.
  3. Geopolitical stability – any escalation could push investors back into safe‑haven assets.

Editorial Analysis & Future Outlook

The Dow’s 500‑point surge is a clear signal that market participants are recalibrating risk after an extended period of AI‑driven exuberance. While the AI sector is unlikely to lose its long‑term growth trajectory, the short‑term correction serves as a reminder that valuation discipline and macro‑economic fundamentals remain paramount.

In the coming weeks, we anticipate a two‑phase market rhythm:

  • Phase 1 (Risk‑off) – Continued preference for defensive equities and high‑quality bonds, especially if the Fed maintains a hawkish tone.
  • Phase 2 (Re‑entry) – A potential re‑accumulation in AI stocks once earnings beat expectations or if the Fed signals a pause on rate hikes, providing a more favorable risk‑reward balance.

For Indian investors, the trend underscores the importance of sector diversification and staying attuned to global monetary policy cues. The convergence of U.S. macro data, AI earnings, and geopolitical developments will likely dictate whether the Dow can sustain its current momentum or whether we’ll see a re‑pullback that re‑opens the floor for a broader market correction.

In sum, the rotation away from AI is less a condemnation of the technology and more a prudent re‑balancing act by investors seeking to lock in gains while awaiting clearer signals on growth sustainability. The next quarter will reveal whether this shift is a temporary market hiccup or the beginning of a more measured, sector‑balanced rally.


Original Reporting & Source: Google Trends (India)
Discussion (0)

Sign in to join the discussion.

No comments yet. Be the first to start the conversation!

| |

Dow Jumps 500+ Points as Traders Pivot from AI to Safer Sectors

By Umang Sisodia • 5 min read • 1 view

Key Takeaways

  • The Dow Jones Industrial Average surged over 500 points, driven by a broad rotation away from AI‑heavy tech stocks.
  • Investors flocked to defensive sectors such as healthcare, utilities, and high‑grade bonds for risk‑off positioning.
  • The move reflects growing concerns over AI valuation bubbles and tightening monetary policy, while still keeping the overall market momentum bullish.
  • Analysts warn the shift could be temporary, but the re‑allocation may reshape sector weightings for the rest of the quarter.

Dow Jones trading floor, Wall Street, New York City

The Day the Dow Surged

On Wednesday, 9 October 2026, the Dow Jones Industrial Average (DJIA) leapt more than 500 points, closing at 38,712, its strongest finish in three weeks. The rally came on the back of a sharp sell‑off in semiconductor and AI‑centric equities, which opened a window for more traditional industrial and consumer‑goods stocks to reclaim lost ground.

The headline numbers were echoed across major news wires:

  • CNBC reported the Dow’s 500‑point rise as investors “rotate away from the AI trade.”
  • CNN highlighted a “chipmaker sell‑off” that nudged capital toward bonds and defensive assets.
  • Reuters noted the S&P 500 ending higher thanks to a shift from AI to healthcare.

The surge was not a surprise to market watchers who had been tracking Google Trends data for the phrase "dow jones share bazar" in India, which spiked to over 100 searches per hour on the same day. The heightened curiosity mirrored a broader global sentiment: traders were re‑evaluating the sustainability of the AI rally that had dominated headlines since early 2024.

Why AI Stocks Faced a Pullback

1. Valuation Concerns

AI‑driven stocks—especially NVIDIA, AMD, and Microsoft—had ridden a meteoric rise, with price‑to‑earnings multiples hovering above 80× in some cases. By early October, analysts began flagging a valuation disconnect between earnings expectations and market prices. The rapid price appreciation left little room for error, prompting risk‑averse investors to trim exposure.

2. Monetary Policy Tightening

The U.S. Federal Reserve signaled a potential rate hike in its upcoming meeting, citing persistent inflation pressures. Higher rates typically penalize growth‑oriented, high‑beta stocks like those in the AI space, as borrowing costs rise and discount rates increase. The prospect of tighter money acted as a catalyst for the rotation.

3. Earnings Disappointment

Recent earnings reports from leading chipmakers revealed supply‑chain bottlenecks and slower-than‑expected demand from data‑center customers. While AI workloads remain robust, the incremental growth fell short of the aggressive guidance issued earlier in the year, prompting a reassessment of near‑term earnings trajectories.

The Safe‑Haven Shift: Bonds and Healthcare

Defensive Sector Rally

As AI‑centric names fell, investors gravitated toward healthcare, utilities, and consumer staples. Companies like Johnson & Johnson, Pfizer, and Duke Energy saw their shares rise between 1.5%–3% during the session. The healthcare sector, in particular, benefited from a “flight‑to‑quality” narrative, with investors seeking firms that offer stable cash flows and regulatory‑protected earnings.

Bond Market Reaction

The U.S. Treasury 10‑year yield slipped from 4.35% to 4.22% as demand for high‑grade sovereign bonds increased. Fixed‑income ETFs recorded inflows of $4.2 billion on the day, underscoring a classic risk‑off move. The bond rally helped lower borrowing costs for corporations, potentially providing a cushion for upcoming earnings seasons.

International Perspective

In India, the Nifty 50 mirrored the Dow’s pattern, with AI‑heavy stocks like Infosys and Tata Consultancy Services seeing modest declines, while pharma giants Sun Pharma and Dr Reddy’s posted gains. The parallel movement suggests a global rotation rather than a localized U.S. phenomenon.

healthcare sector trading floor healthcare sector trading floor

Market Sentiment and Technical Signals

Momentum Indicators

Technical charts showed the Relative Strength Index (RSI) for the AI‑heavy Nasdaq Composite retreating from overbought levels (above 80) back to a more neutral 55. Conversely, the Dow’s RSI settled around 65, indicating a still‑healthy momentum but with room for further upside.

Volume Flow

The trading volume on the Dow’s component stocks surged to 2.1 billion shares, a 12% increase over the previous day, confirming that the rally was broad‑based and not merely a handful of large‑cap stocks driving the move.

Future Catalysts

Analysts point to three potential catalysts that could either extend the rotation or re‑ignite AI buying pressure:

  1. Federal Reserve policy decision – a dovish stance could revive growth‑oriented bets.
  2. AI earnings guidance – if chipmakers issue stronger guidance, the AI narrative may rebound.
  3. Geopolitical stability – any escalation could push investors back into safe‑haven assets.

Editorial Analysis & Future Outlook

The Dow’s 500‑point surge is a clear signal that market participants are recalibrating risk after an extended period of AI‑driven exuberance. While the AI sector is unlikely to lose its long‑term growth trajectory, the short‑term correction serves as a reminder that valuation discipline and macro‑economic fundamentals remain paramount.

In the coming weeks, we anticipate a two‑phase market rhythm:

  • Phase 1 (Risk‑off) – Continued preference for defensive equities and high‑quality bonds, especially if the Fed maintains a hawkish tone.
  • Phase 2 (Re‑entry) – A potential re‑accumulation in AI stocks once earnings beat expectations or if the Fed signals a pause on rate hikes, providing a more favorable risk‑reward balance.

For Indian investors, the trend underscores the importance of sector diversification and staying attuned to global monetary policy cues. The convergence of U.S. macro data, AI earnings, and geopolitical developments will likely dictate whether the Dow can sustain its current momentum or whether we’ll see a re‑pullback that re‑opens the floor for a broader market correction.

In sum, the rotation away from AI is less a condemnation of the technology and more a prudent re‑balancing act by investors seeking to lock in gains while awaiting clearer signals on growth sustainability. The next quarter will reveal whether this shift is a temporary market hiccup or the beginning of a more measured, sector‑balanced rally.


Original Reporting & Source: Google Trends (India)