Umang Sisodia • • 5 min read • 3 views

EPFO’s ₹25,000 crore AIF Push: What It Means for 30 Crore PF Subscribers
Listen to Article
Select a voice and press play
EPFO’s ₹25,000 crore AIF Push: What It Means for 30 Crore PF Subscribers

Key Takeaways

  • EPFO plans to channel over ₹25,000 crore of employee savings into Alternative Investment Funds (AIFs), marking the largest single‑investment move in its history.
  • More than 30 crore PF subscribers stand to benefit from higher, market‑linked returns, but the shift also raises questions about risk exposure and regulatory oversight.
  • The announcement has surged on Google Trends because it touches every salaried Indian, sparking debates on safety, returns, and the future of the Provident Fund system.
  • Experts predict a two‑phase rollout: pilot schemes in select states followed by a nationwide implementation, potentially reshaping India’s retirement‑savings landscape.

The EPFO's Historic AIF Initiative

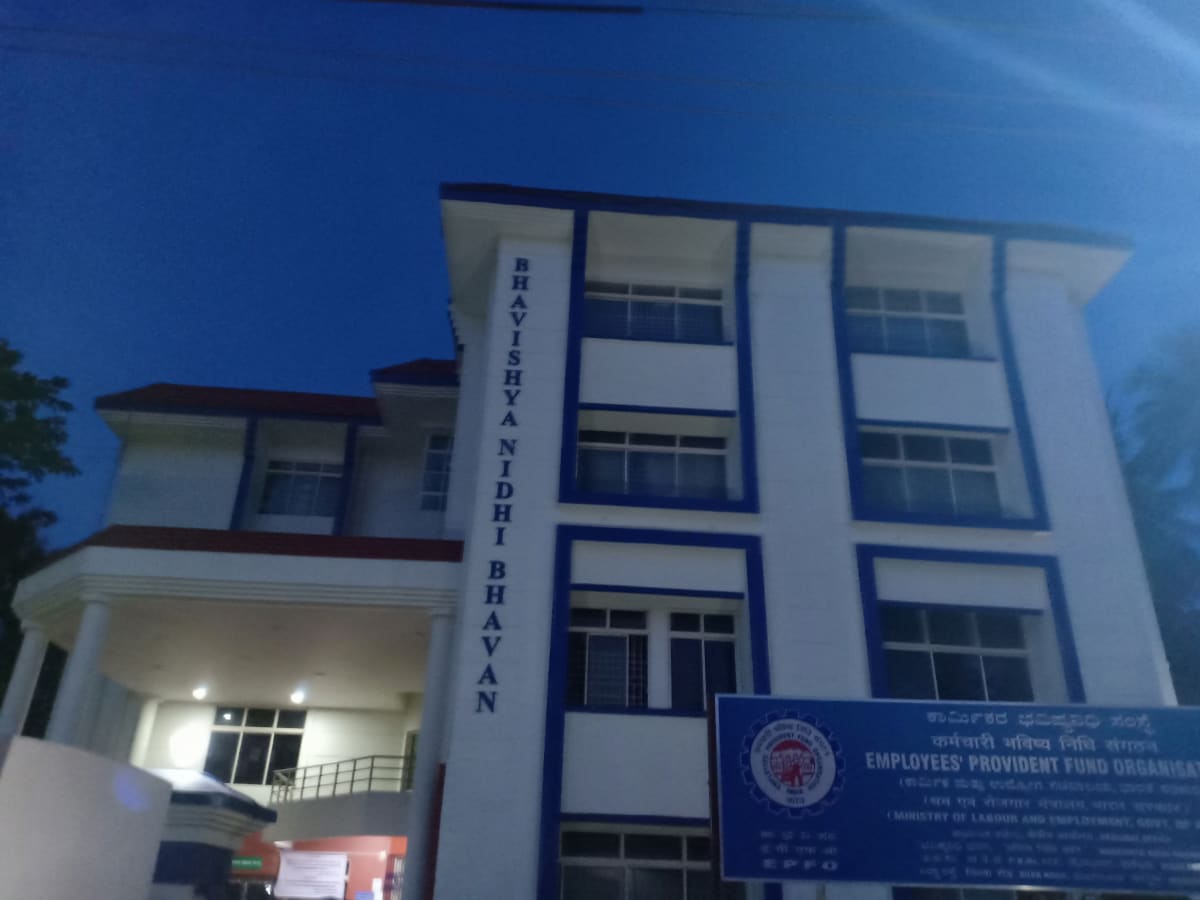
The Employees' Provident Fund Organisation (EPFO), a statutory body that manages the retirement savings of the nation’s salaried workforce, announced a bold plan to create an Alternative Investment Fund (AIF) worth ₹25,000 crore. This fund will be sourced primarily from the unclaimed and surplus balances of more than 30 crore EPF members.

"Our objective is to enhance returns for PF subscribers while shielding them from market volatility through a professionally managed AIF," said Ashish Kumar Gupta, EPFO’s Director‑General, during a press briefing in New Delhi.

The move diverges from the traditional, government‑guaranteed 8.5 % interest that EPF accounts earn. By tapping into AIFs—investment vehicles that can allocate capital to private equity, infrastructure, and debt markets—EPFO hopes to bridge the gap between safety and higher yields.


  1. Scale of Impact – With 30 crore (300 million) employees, the EPF is the single largest retirement corpus in the world. Any policy shift automatically becomes a national conversation.
  2. Search Spike – Google Trends shows a 2000+ search surge for "कर्मचारी भविष्य निधि संगठन" within a single day, reflecting public curiosity and concern.
  3. Media Amplification – Leading Hindi dailies such as Hindustan, Jagran, and Navbharat Times have run front‑page stories, each framing the move as either a "good news" or a "potential risk".
  4. Policy Timing – The announcement coincides with the union budget’s focus on financial inclusion and the government’s push for greater private‑sector participation in retirement savings.


Market Reaction and Stakeholder Perspectives

  • Financial Analysts: Most analysts view the AIF as a strategic diversification. A report by Motilal Oswal estimates that a well‑managed AIF could push effective PF returns to 10‑12 % over a five‑year horizon.
  • Employee Unions: Groups like the All India Bank Employees Association (AIBEA) have raised concerns about exposure to market downturns, urging EPFO to retain a minimum guaranteed return.
  • Regulators: The Securities and Exchange Board of India (SEBI) has clarified that EPFO‑sponsored AIFs will fall under Category‑III AIFs, which are restricted to professional investors and must adhere to strict risk‑management norms.
  • Corporate Sponsors: Several mutual fund houses have expressed interest in managing the fund, citing EPFO’s massive capital as a game‑changer for India’s AIF ecosystem.

Potential Benefits for PF Subscribers

  • Higher Returns: Market‑linked assets can outpace the static 8.5 % rate, especially in infrastructure and green energy projects that are currently receiving policy incentives.
  • Diversification: By spreading deposits across equity, debt, and real‑estate, the fund can mitigate concentration risk inherent in a single‑asset model.
  • Liquidity Options: EPFO plans to allow partial withdrawals after a five‑year lock‑in, giving retirees more flexibility than the current scheme.

Risks and Mitigation Strategies

  • Market Volatility: AIFs are subject to price swings. EPFO intends to hedge a portion of the portfolio using government securities and derivative instruments.
  • Governance: The fund will be overseen by a tripartite board—representatives from EPFO, SEBI, and an independent financial expert—to ensure transparent decision‑making.
  • Regulatory Compliance: As a Category‑III AIF, the fund must maintain 100 % investor protection, limiting exposure to high‑risk assets.

Implementation Roadmap and Timeline

Phase Timeline Key Actions
Pilot Q4 2024 – Q2 2025 Launch AIF in four states (Maharashtra, Karnataka, Delhi, Tamil Nadu). Test fund allocation models and subscriber onboarding.
Scale‑Up Q3 2025 – Q4 2026 Expand to all states, integrate digital enrollment via the EPFO portal, and introduce real‑time performance dashboards for subscribers.
Full Roll‑Out FY 2027 Achieve ₹25,000 crore corpus, establish annual audit by a top‑tier accounting firm, and publish transparent performance reports.

Editorial Analysis & Future Outlook

The EPFO’s foray into AIFs could redefine retirement savings for India’s burgeoning middle class. By leveraging private‑sector expertise, the fund promises higher, inflation‑adjusted returns that traditional PF accounts struggle to deliver. However, the success of this initiative hinges on robust governance, clear communication, and safeguards against market shocks.

If EPFO manages to balance risk and reward, it may set a precedent for other statutory bodies—such as the Employees' State Insurance (ESI) and **National Pension System (NPS)**—to explore similar hybrid investment models. In the long run, a well‑executed AIF could boost national savings, funnel capital into critical infrastructure, and enhance financial inclusion.

Conversely, any misstep—like a significant loss during a market correction—could erode public trust, prompting political backlash and potentially tightening regulatory scrutiny. Therefore, transparent reporting, periodic audits, and subscriber education will be paramount.

In summary, the EPFO’s ₹25,000 crore AIF plan is a high‑stakes gamble that, if played wisely, could usher in a new era of wealth creation for millions of Indian workers. The coming months will reveal whether this bold experiment will deliver on its promise or become a cautionary tale in the annals of public finance.


Original Reporting & Source: Google Trends (India)
Discussion (0)

Sign in to join the discussion.

No comments yet. Be the first to start the conversation!

| |

EPFO’s ₹25,000 crore AIF Push: What It Means for 30 Crore PF Subscribers

By Umang Sisodia • 5 min read • 3 views

Key Takeaways

  • EPFO plans to channel over ₹25,000 crore of employee savings into Alternative Investment Funds (AIFs), marking the largest single‑investment move in its history.
  • More than 30 crore PF subscribers stand to benefit from higher, market‑linked returns, but the shift also raises questions about risk exposure and regulatory oversight.
  • The announcement has surged on Google Trends because it touches every salaried Indian, sparking debates on safety, returns, and the future of the Provident Fund system.
  • Experts predict a two‑phase rollout: pilot schemes in select states followed by a nationwide implementation, potentially reshaping India’s retirement‑savings landscape.

The EPFO's Historic AIF Initiative

The Employees' Provident Fund Organisation (EPFO), a statutory body that manages the retirement savings of the nation’s salaried workforce, announced a bold plan to create an Alternative Investment Fund (AIF) worth ₹25,000 crore. This fund will be sourced primarily from the unclaimed and surplus balances of more than 30 crore EPF members.

"Our objective is to enhance returns for PF subscribers while shielding them from market volatility through a professionally managed AIF," said Ashish Kumar Gupta, EPFO’s Director‑General, during a press briefing in New Delhi.

The move diverges from the traditional, government‑guaranteed 8.5 % interest that EPF accounts earn. By tapping into AIFs—investment vehicles that can allocate capital to private equity, infrastructure, and debt markets—EPFO hopes to bridge the gap between safety and higher yields.


  1. Scale of Impact – With 30 crore (300 million) employees, the EPF is the single largest retirement corpus in the world. Any policy shift automatically becomes a national conversation.
  2. Search Spike – Google Trends shows a 2000+ search surge for "कर्मचारी भविष्य निधि संगठन" within a single day, reflecting public curiosity and concern.
  3. Media Amplification – Leading Hindi dailies such as Hindustan, Jagran, and Navbharat Times have run front‑page stories, each framing the move as either a "good news" or a "potential risk".
  4. Policy Timing – The announcement coincides with the union budget’s focus on financial inclusion and the government’s push for greater private‑sector participation in retirement savings.


Market Reaction and Stakeholder Perspectives

  • Financial Analysts: Most analysts view the AIF as a strategic diversification. A report by Motilal Oswal estimates that a well‑managed AIF could push effective PF returns to 10‑12 % over a five‑year horizon.
  • Employee Unions: Groups like the All India Bank Employees Association (AIBEA) have raised concerns about exposure to market downturns, urging EPFO to retain a minimum guaranteed return.
  • Regulators: The Securities and Exchange Board of India (SEBI) has clarified that EPFO‑sponsored AIFs will fall under Category‑III AIFs, which are restricted to professional investors and must adhere to strict risk‑management norms.
  • Corporate Sponsors: Several mutual fund houses have expressed interest in managing the fund, citing EPFO’s massive capital as a game‑changer for India’s AIF ecosystem.

Potential Benefits for PF Subscribers

  • Higher Returns: Market‑linked assets can outpace the static 8.5 % rate, especially in infrastructure and green energy projects that are currently receiving policy incentives.
  • Diversification: By spreading deposits across equity, debt, and real‑estate, the fund can mitigate concentration risk inherent in a single‑asset model.
  • Liquidity Options: EPFO plans to allow partial withdrawals after a five‑year lock‑in, giving retirees more flexibility than the current scheme.

Risks and Mitigation Strategies

  • Market Volatility: AIFs are subject to price swings. EPFO intends to hedge a portion of the portfolio using government securities and derivative instruments.
  • Governance: The fund will be overseen by a tripartite board—representatives from EPFO, SEBI, and an independent financial expert—to ensure transparent decision‑making.
  • Regulatory Compliance: As a Category‑III AIF, the fund must maintain 100 % investor protection, limiting exposure to high‑risk assets.

Implementation Roadmap and Timeline

Phase Timeline Key Actions
Pilot Q4 2024 – Q2 2025 Launch AIF in four states (Maharashtra, Karnataka, Delhi, Tamil Nadu). Test fund allocation models and subscriber onboarding.
Scale‑Up Q3 2025 – Q4 2026 Expand to all states, integrate digital enrollment via the EPFO portal, and introduce real‑time performance dashboards for subscribers.
Full Roll‑Out FY 2027 Achieve ₹25,000 crore corpus, establish annual audit by a top‑tier accounting firm, and publish transparent performance reports.

Editorial Analysis & Future Outlook

The EPFO’s foray into AIFs could redefine retirement savings for India’s burgeoning middle class. By leveraging private‑sector expertise, the fund promises higher, inflation‑adjusted returns that traditional PF accounts struggle to deliver. However, the success of this initiative hinges on robust governance, clear communication, and safeguards against market shocks.

If EPFO manages to balance risk and reward, it may set a precedent for other statutory bodies—such as the Employees' State Insurance (ESI) and **National Pension System (NPS)**—to explore similar hybrid investment models. In the long run, a well‑executed AIF could boost national savings, funnel capital into critical infrastructure, and enhance financial inclusion.

Conversely, any misstep—like a significant loss during a market correction—could erode public trust, prompting political backlash and potentially tightening regulatory scrutiny. Therefore, transparent reporting, periodic audits, and subscriber education will be paramount.

In summary, the EPFO’s ₹25,000 crore AIF plan is a high‑stakes gamble that, if played wisely, could usher in a new era of wealth creation for millions of Indian workers. The coming months will reveal whether this bold experiment will deliver on its promise or become a cautionary tale in the annals of public finance.


Original Reporting & Source: Google Trends (India)